
1. Executive Summary
Credicorp Ltd. (NYSE: BAP) represents the apex financial services holding company in the Republic of Peru. Operating through its flagship universal banking subsidiary, Banco de Crédito del Perú (BCP), alongside its microfinance arm (Mibanco), insurance and pensions division (Grupo Pacífico, Prima AFP), and wealth management unit (Credicorp Capital), the enterprise functions as the central nervous system of the Peruvian economy.1 Valued at approximately $27.3 billion with a trailing Price-to-Earnings (P/E) multiple of 14.3x and a Price-to-Book (P/B) multiple of 2.1x 3, Credicorp embodies the classic characteristics of an emerging market oligopoly compounder. The fundamental investment thesis for Credicorp necessitates a rigorous, objective assessment of its structural competitive advantages, the sustainability of its growth trajectory through aggressive digital disruption, and the efficacy of management’s capital allocation in a chronically volatile macroeconomic environment.
The bullish perspective on Credicorp is predicated on the existence of an extraordinarily wide and deep economic moat derived from its unparalleled scale, dense distribution network, and dominant deposit franchise in Peru. With a 34.5% market share in total system loans and a 31.8% share in deposits as of early 2025 5, BCP operates with a profound, structural cost-of-funding advantage. This low-cost liability base—where 73.0% of total deposits are classified as low-cost demand and savings accounts 6—insulates the company’s net interest margin (NIM) against monetary easing cycles and heavily subsidizes organic growth. Furthermore, the company has successfully self-disrupted through its proprietary digital wallet, Yape. Reaching 15.9 million monthly active users (MAUs) and processing over 66 transactions per user monthly in late 2025 6, Yape has transitioned from a loss-leading peer-to-peer payment application into a highly monetizable super-app. Lending now accounts for 23% of Yape’s revenue, driving the holding company’s innovation portfolio to generate 8.1% of the group’s total risk-adjusted revenues.6 This digital infrastructure structurally lowers customer acquisition costs (CAC), expands the total addressable market (TAM) deep into the underbanked informal economy, and provides a runway for structural growth that outpaces underlying Peruvian GDP.
Conversely, the bearish perspective highlights that this investment case is heavily clouded by chronic systemic risks, value-dilutive international expansions, and escalating operational expenditures. Peru’s political landscape remains inherently fragile heading into the April 2026 general elections, with a historically fragmented electorate and a high percentage of undecided voters creating a persistent risk premium on all Peruvian assets. Economically, while the national GDP recovered to a 3.5% growth rate in 2025 9, the microfinance segment (Mibanco) remains highly sensitive to localized macroeconomic shocks, such as El Niño weather disruptions and persistent inflation that disproportionately affects the lower-income demographic.11 Furthermore, Credicorp’s aggressive digital investments have driven group operating expenses up by 12.0% year-over-year in 2025, pushing the consolidated efficiency ratio to a bloated 46.6%.6 The systemic risk remains that the rapid scaling of unseasoned, algorithmic digital consumer loans through Yape could eventually yield adverse selection and elevated non-performing loans (NPLs) if the macro environment deteriorates, testing the underwriting algorithms that currently report a seemingly pristine cost of risk. Finally, geographic diversification efforts—such as the structurally struggling Mibanco Colombia unit, which reported a -2.0% ROE in 2024 13, and the premium 1.68x tangible book value paid for the US-based Helm Bank 14—suggest that capital deployed outside the core Peruvian banking oligopoly earns distinctly sub-par returns.
Ultimately, Credicorp is a highly superior business trading at a fair, albeit fully priced, market multiple. The enterprise’s ability to sustain a consolidated Return on Equity (ROE) of 19.0% for the full year 2025 firmly validates the existence of its competitive advantage.6 The primary determinant of long-term shareholder value will be management’s ability to leverage Yape’s network effects to drive incremental lending revenues without severely compromising the consolidated efficiency ratio or sacrificing strict underwriting standards.
2. Competitive Advantage Assessment
A business operating without a structural competitive advantage cannot mathematically sustain excess returns on invested capital over a prolonged duration. In the commercial banking sector, a competitive advantage typically manifests in one of three ways: a structurally low-cost deposit franchise (a liability advantage), superior, proprietary underwriting capabilities (an asset advantage), or insurmountable economies of scale that relentlessly drive down non-interest operating costs relative to peers (an efficiency advantage). An objective analysis of Credicorp demonstrates overwhelming evidence of both liability and scale advantages within its domestic market.
The Peruvian banking sector functions as a highly concentrated oligopoly, heavily barricaded against new entrants. The top four financial institutions—BCP, BBVA Peru, Scotiabank Peru, and Interbank—collectively control over 80% of total banking system assets.15 Within this consolidated structure, Credicorp’s universal banking subsidiary, BCP, is the undisputed apex institution. As of early 2025, BCP controls approximately 34.5% of the total loan market and 31.8% of the deposit market in Peru.5 To contextualize this dominance, BCP’s closest rival, the Spanish-owned BBVA Peru, holds a 21.8% market share in total loans and a 20.8% share in total deposits.17 Interbank (owned by Intercorp Financial Services) and Scotiabank Peru trail significantly further behind.18 Credicorp’s market dominance extends beyond universal banking; its microfinance subsidiary, Mibanco, holds a commanding 29% market share in its specific segment, while its insurance arm, Pacifico Seguros, leads the non-life insurance market with a 26.2% premium share.5
This sheer scale provides BCP with a massive physical distribution network consisting of over 1,200 branch locations and 10,500 ATMs nationwide.5 This physical footprint establishes a formidable, capital-intensive barrier to entry for prospective challengers. However, in the modern financial era, physical density must be augmented by digital dominance to maintain relevance. Through the seamless integration of BCP’s core banking architecture and the Yape digital wallet, Credicorp commands the primary transactional hub of the Peruvian economy, executing 47% of the total amount transacted in the entire Peruvian banking system during peak periods.20
The most definitive, empirical proof of a banking moat is the blended cost of liabilities. Credicorp’s deposit mix is structurally superior to every domestic peer. At the conclusion of fiscal year 2025, an astonishing 73.0% of the holding company’s total deposits were classified as low-cost, consisting of zero-yield demand deposits and low-yield savings accounts.6 This massive base of essentially free funding allows BCP to generate a consolidated cost of funds of merely 2.3%.6 This is a profound advantage, particularly in an environment where the Central Reserve Bank of Peru (BCRP) benchmark rate hovered around 5.00% at the end of 2024 and remained elevated throughout 2025.21 Because BCP serves as the primary operating and payroll account for a vast plurality of Peruvian corporations and retail consumers, cash naturally pools on its balance sheet. When a corporate client executes payroll, the funds routinely transfer from a BCP corporate account directly to a BCP retail account, never leaving the Credicorp ecosystem. This closed-loop velocity minimizes funding leakage and effectively immunizes the bank’s net interest margin (NIM) against aggressive, price-based competition on the asset side of the balance sheet.
A theoretical competitive advantage must translate into superior unit economics and absolute financial outperformance to be deemed investable. Credicorp’s historical financial metrics unequivocally substantiate its dominance when compared to domestic and regional peers. For the full year 2025, Credicorp reported a consolidated ROE of 19.0%.6 More impressively, analyzing the core franchise in isolation reveals that BCP Stand-alone generated a staggering full-year ROE of 24.7%.7 By comparison, its primary domestic competitor, BBVA Peru, reported a lower, albeit respectable, ROE of 17.9% through the first nine months of 2025.17 Intercorp Financial Services (IFS), the parent company of Interbank, reported a 2025 ROE of 16.8%.22 Scotiabank Peru has persistently struggled to match the unit economics of the local leaders, with its broader international segment (heavily weighted to operations in Peru and Chile) generating a structurally inferior 12.8% ROE.19
Furthermore, Credicorp’s consolidated Net Interest Margin (NIM) stood at a highly robust 6.62% in Q4 2025, with a Risk-Adjusted NIM (which factors in the cost of risk and provisioning) reaching a record high of 5.55%.6 This margin profile is a direct mathematical output of the 2.3% cost of funds combined with a deliberate strategic shift toward higher-yielding retail and microfinance lending on the asset side.6 The evidence overwhelmingly concludes that Credicorp’s competitive advantages are deeply structural rather than cyclical. They do not stem from excessive balance sheet leverage or aggressive, under-provisioned risk-taking, but rather from an impenetrable, low-cost deposit franchise and inescapable network effects embedded within the Peruvian transactional ecosystem.
3. Industry Dynamics & Structural Changes
To accurately project Credicorp’s future cash flows, one must analyze the unique structural characteristics, macroeconomic realities, and regulatory shifts within the Peruvian and broader Latin American banking markets. The operating environment is characterized by high structural growth potential, counterbalanced by persistent political fragility.
Following a period of severe economic and social volatility in 2023—characterized by a 0.6% GDP contraction triggered by violent political protests and an unexpected Coastal El Niño weather phenomenon that devastated agricultural and fishing outputs 11—Peru’s macroeconomic fundamentals have demonstrated remarkable resilience and stabilization. National GDP rebounded to 3.2% in 2024 23 and expanded by an estimated 3.5% in 2025, driven by strong domestic demand, resilient household consumption, and record-high mineral exports exceeding $90 billion.9 Inflation, which peaked at a disruptive 8.5% in late 2022, was aggressively and competently managed by the BCRP. Through a series of orthodox monetary tightening measures followed by cautious easing, inflation fell back within the central bank’s target range of 1% to 3%, closing 2024 near 2.0% and remaining subdued through 2025.11
Unlike neighboring Argentina, which suffers from chronic hyperinflation and a virtually non-existent private credit market (with private sector debt languishing at a mere 34.9% of GDP) 24, Peru maintains a highly orthodox, investment-grade monetary framework. The sovereign boasts abundant international reserves representing over 24% of GDP and maintains low gross public debt at approximately 31% of GDP.25 This foundational macroeconomic stability creates a predictable, albeit occasionally noisy, environment for bank capitalization, duration transformation, and long-term loan underwriting.
The primary structural growth engine for the entire Peruvian banking sector is the ongoing process of financial deepening. “Bankarization”—defined as the ratio of gross system loans to national GDP—has historically hovered between 40% and 50% in Peru.15 This penetration rate is substantially lower than those found in developed markets and even lags behind regional peers like Chile, representing a massive, multi-decade runway for organic total addressable market (TAM) expansion. A significant portion of the Peruvian labor force operates entirely within the informal economy, historically relying exclusively on physical cash for commerce and savings.
However, the global pandemic and the subsequent aggressive rollout of digital wallets forcefully accelerated financial inclusion across the nation. According to the World Bank Global Findex, account ownership in developing economies like Peru surged dramatically from 2011 to 2021.28 Credicorp management claims that the enterprise alone has successfully included 5.7 million previously unbanked individuals into the formal financial system through BCP and Yape since 2020.23 The formalization of this demographic transitions them from unbanked citizens to entry-level payment users, and eventually, through data-driven underwriting, into highly profitable credit consumers.
The most profound structural change currently reshaping Latin American banking is the rapid proliferation of digital wallets and neobanks. While the central bank-mandated Pix system revolutionized payments in Brazil, the equivalent digital disruption in Peru has been entirely led by private enterprise, specifically Credicorp’s Yape and the competing banking consortium’s platform, Plin (backed jointly by BBVA, Interbank, and Scotiabank).30 Initially launched by BCP in 2016 as a simple peer-to-peer (P2P) mobile payment tool, Yape has achieved near-ubiquity in the domestic market. By the fourth quarter of 2025, Yape reached an extraordinary 15.9 million MAUs—representing nearly 80% of Peru’s total economically active population.6 While the competing Plin platform also boasts significant scale (reaching approximately 13 million users by 2024), Yape thoroughly dominates in user engagement, processing roughly six times the transaction volume of Plin.31
A critical regulatory inflection point for the digital payments landscape occurred in 2023 when the Peruvian Central Bank (BCRP) formally mandated complete payment interoperability between Yape and Plin.31 Rather than commoditizing Yape and stripping its network effect advantage, interoperability actually cemented Yape’s status as the default operating system for daily Peruvian commerce. It allowed Yape to aggressively pivot away from mere user acquisition and toward high-margin monetization via micro-lending, marketplace integration, and B2B enterprise services. Consequently, the existential threat of pure-play, venture-backed neobanks capturing the Peruvian market has been largely neutralized. Credicorp willingly cannibalized its own legacy fee structures to scale Yape rapidly, effectively building a digital moat that standalone fintechs cannot breach without massive, prohibitive customer acquisition subsidies.
On the regulatory front, the landscape in Peru is systematically transitioning toward the stringent Basel III international capital standards. The Superintendency of Banks, Insurance and Private Pension Funds (SBS) prudently delayed the full implementation deadline to allow domestic banks sufficient time to adjust their capital structures, with the phase-in timeline now extending through 2027.15 The new regulatory framework actively tightens the definition of risk-weighted assets (RWA) and introduces mandatory capital conservation and countercyclical buffers. Credicorp, however, operates from a position of massive regulatory capital surplus. As of Q4 2025, BCP reported a robust IFRS Common Equity Tier 1 (CET1) ratio of 13.99%, while the riskier Mibanco subsidiary reported a remarkably high CET1 ratio of 17.30%.6 These capital ratios sit comfortably above the revised regulatory minimums, ensuring that the finalization of Basel III implementation will absolutely not constrain Credicorp’s ability to grow risk assets, originate new loans, or return excess capital to shareholders via dividends.
4. Growth Analysis
A structural competitive advantage without an accompanying avenue for secular growth severely limits the capacity for long-term capital compounding. Credicorp’s historical financial performance demonstrates a proven, resilient ability to consistently grow its balance sheet. However, the underlying composition of that growth is shifting fundamentally, transitioning from traditional, physical branch-based origination to frictionless, digital algorithmic lending.
Over the past decade, Credicorp has delivered highly commendable top and bottom-line expansion. The holding company’s consolidated net income expanded from $986 million in the fiscal year 2015 to approximately $1.8 billion (S/6,925.4 million) for the full year 2025.6 This substantial earnings growth was largely driven by expanding net interest income over the decade. In 2025 alone, total consolidated loans grew by 8.5% year-over-year on a constant-currency, Bolivia-adjusted basis.6
The intrinsic quality of this loan growth has been thoroughly impressive. Management has actively and deliberately shifted the overall portfolio mix toward higher-yielding retail segments, consumer loans, and small-to-medium enterprises (SMEs), while simultaneously reducing aggregate exposure to low-margin, highly competitive corporate wholesale lending. Traditional banking theory dictates that targeting higher-yielding retail segments inherently requires assuming a higher cost of risk. Yet, despite this strategic pivot, Credicorp’s asset quality actually improved significantly in recent periods. The consolidated Non-Performing Loan (NPL) ratio fell by a material 71 basis points year-over-year, landing at 4.5% at the end of 2025.6 Furthermore, the consolidated cost of risk declined sharply from 2.4% in 2024 to 1.6% in 2025 6, aided by a highly conservative NPL coverage ratio of 112.4%.8 This combination of metrics conclusively indicates that Credicorp is not recklessly sacrificing underwriting standards simply to manufacture top-line loan growth. Rather, enhanced, AI-driven discriminatory risk models are successfully isolating prime and near-prime borrowers within the broader retail strata, allowing for profitable expansion without the associated credit blowouts.6
The future growth narrative of Credicorp is inextricably linked to the continued monetization of the Yape ecosystem. Yape represents the nucleus of the enterprise’s forward-looking growth strategy. As a standalone business unit, Yape nearly doubled its total income in 2025, reaching S/1,260.3 million.6 The unit economics of this digital platform are highly compelling and are actively demonstrating operating leverage: by Q4 2025, the monthly revenue per active user (ARPU) rose to S/9.6, meaningfully outpacing the monthly expense per active user, which stood at S/6.1.6
The primary engine driving Yape’s monetization is algorithmic micro-lending. In the fourth quarter of 2025, high-margin lending represented 23% of Yape’s total revenues, an aggressive near-doubling from the 12% contribution recorded just one year prior in Q4 2024.6 The platform has successfully disbursed algorithmic loans to over 4.1 million individual clients.6 By utilizing proprietary alternative data—such as utility payment histories, digital transaction frequency, and granular cell phone metadata—Credicorp can effectively underwrite informal workers who entirely lack a traditional credit bureau history.32 This structural informational advantage drops the marginal cost of loan origination to near zero, allowing the bank to profitably service micro-loans that would be economically unviable for traditional branch networks.32
Management’s publicly stated aspiration is to steadily increase the average lending ticket size on the Yape platform from roughly S/200 to over S/500, while concurrently driving the broader innovation portfolio to contribute 10% of the group’s total risk-adjusted revenue by 2026.32 Given that the innovation portfolio already achieved an 8.1% contribution share in Q4 2025 6, this 10% target is highly credible and represents a structural upgrade to the company’s long-term earnings power.
However, while the domestic Peruvian operations are stellar, Credicorp’s geographic expansion efforts outside its home market present a highly mixed, and often dilutive, track record.
- Bolivia: BCP Bolivia faces severe, ongoing macroeconomic headwinds, including a contracting national GDP, persistent fiscal imbalances, a critically low level of international reserves, and localized inflation approaching 20%. The Bolivian asset base required significant accounting revaluations in 2025 to reflect massive currency depreciation against the US Dollar.6 It remains a persistent drag on consolidated returns and consumes disproportionate management bandwidth.
- Colombia: Mibanco Colombia has severely underperformed expectations. In 2024, the unit reported a destructive negative ROAE of -2.0%.13 Despite aggressive cost-cutting measures that brought the localized efficiency ratio down from 93% to 77% 13, the incredibly high cost of risk (5.9%) and elevated NPLs (6.2%) 13 heavily suggest that exporting the Peruvian microfinance relationship-lending model to the Colombian market has encountered severe cultural and operational friction.
- Chile: Credicorp is finding significantly better traction in the more developed Chilean market via purely digital avenues. Its subsidiary, Tenpo, received a formal banking license from regulators in early 2026, officially making it Chile’s first licensed neobank, boasting an existing user base of over 2.5 million clients.6 This provides Credicorp with a regulated platform to capture low-cost deposits in a highly banked market without the capital expenditure required to build physical branches.
Ultimately, the empirical evidence dictates that Credicorp’s international operations currently serve more as a distraction than a primary value driver. They contribute marginally to the consolidated bottom line while introducing outsized macroeconomic volatility and depressing the group’s overall return on capital. The true growth engine remains firmly within the borders of Peru.
5. Capital Allocation & Shareholder Value Creation
Management’s capital allocation framework is the vital bridge between a high-ROE business model and realized, per-share value creation for minority investors. If an executive team extracts billions in cash from a 25% ROE core banking franchise only to destroy it in value-dilutive offshore acquisitions or vanity projects, the core investment thesis is fundamentally compromised.
Credicorp requires relatively little retained earnings to fund its core organic loan growth due to its high Return on Assets (ROA) and rapid capital velocity. Consequently, the company has historically returned significant excess cash directly to shareholders. The established dividend policy officially targets a payout ratio of 40% to 50% of audited consolidated net earnings.37 In recent years, this policy has translated into a reliable, consistent dividend yield hovering between 3.0% and 4.0%.38 The absolute payout has grown from $2.31 per share in 2016 to $11.01 per share declared in 2025.39 Furthermore, the board has a demonstrated history of declaring special cash dividends when regulatory capital buffers comfortably exceed internal risk thresholds, proving an anti-hoarding mentality.40
However, the assessment of management’s Mergers and Acquisitions (M&A) track record requires intense scrutiny. In December 2025, Credicorp announced the acquisition of 100% of Helm Bank USA for an aggregate purchase price of $180 million.14 Helm Bank is a relatively small, Florida state-chartered community bank reporting $1.1 billion in total assets and $106.8 million in shareholders’ equity at the time of the announcement.14
An objective, critical analysis of this transaction reveals a mixed picture. Credicorp paid approximately 1.68x tangible book value ($180 million purchase price / $106.8 million equity) for Helm Bank.14 In the context of the fragmented U.S. community banking sector, paying a near 70% premium to tangible book value is exceedingly rich, particularly for a commoditized asset generating standard spread income in a highly competitive Florida market. However, the strategic rationale articulated by management is entirely defensive and synergistic, rather than purely accretive on a standalone return-on-investment basis.
Political volatility in Peru, and the broader Andean region, routinely triggers episodes of capital flight among high-net-worth individuals and nervous corporate treasuries. Historically, when these premium clients panicked, they moved their USD deposits out of BCP and into unaffiliated, offshore banks located in Miami or Panama. By acquiring Helm Bank, Credicorp effectively plugs this systemic leakage. It allows Credicorp’s wealth management arm (Credicorp Capital) to retain full custody of the fleeing assets, offering a seamless, vertically integrated cross-border banking ecosystem for its most lucrative clients. While the initial sticker price is undeniably high, the acquisition protects the perimeter of the broader LatAm ecosystem and captures lucrative, sticky fee income from the affluent demographic that would otherwise be permanently lost to competitors.
Overall, Credicorp’s long-term capital efficiency is world-class for an emerging market financial institution. It has generated an astounding annualized Total Shareholder Return (TSR) of 14.1% over the 30 years since its initial public listing on the NYSE in 1995.42 This exceptional, multi-decade track record serves as empirical proof that management possesses a deep, institutional understanding of intrinsic value and generally refrains from reckless empire-building at the expense of per-share metrics. The publicly stated medium-term target of sustaining a 19.5% ROE alongside a 42% cost-to-income ratio 43 establishes a highly stringent hurdle rate for any future incremental capital deployment.
6. Major Developments & Headwinds (2024–2026)
While the fundamental business quality is exceptional, a critical analyst must heavily weight the immediate macroeconomic and operational headwinds threatening to compress margins or elevate risk.
The most immediate, controllable headwind facing Credicorp is the degradation of its consolidated efficiency ratio. In 2025, total operating expenses surged by 12.0% year-over-year, reaching S/10,426.7 million.6 Because this expense growth significantly outpaced the growth in core banking revenues, the full-year efficiency ratio climbed to an uncomfortable 46.6%.6
Management attributes this cost inflation entirely to deliberate, front-loaded investments required to scale the innovation portfolio (where specific expenses rose 18.4% year-over-year) 6, heavy expenditures related to cloud architecture migration for Yape, the integration of generative AI risk models, and increased compensation for specialized technical headcount.6 While building a proprietary digital moat undeniably requires intense upfront capital expenditure, a 46.6% efficiency ratio is heavy for an institution enjoying such massive, monopolistic scale. The thesis dictates strict monitoring of management’s promise to reverse this trend and drive the efficiency ratio down to a range of 45.0%–46.5% in 2026, and eventually to their long-term target of 42%.7 Failure to demonstrate explicit operating leverage in the second half of 2026 will heavily indicate that the appealing “digital disruption” narrative is actually disguising structural, permanent cost bloat.
Beyond internal cost controls, systemic political instability remains a chronic drag on valuation multiples. Peru enters 2026 facing highly contentious general elections scheduled for April. The political landscape is exceptionally fragmented, with polls indicating over 40% of the electorate remains undecided.9 Historically, Peruvian elections invite aggressive populist rhetoric specifically targeting the highly profitable banking oligopoly and the mandatory private pension system (AFP).
In recent years, the populist Peruvian Congress repeatedly authorized massive, early cash withdrawals from the private pension system. While this provided a massive, short-term liquidity injection into the domestic consumer economy (boosting retail consumption and ironically swelling BCP’s short-term deposits, as the bank captured over $11 billion of the $25 billion withdrawn) 44, it is structurally damaging to the nation’s financial architecture. Successive withdrawals destroy the depth of the domestic capital markets, drastically hurt Prima AFP’s assets under management and fee generation, and reduce the long-term pool of institutional capital available to purchase Peruvian sovereign and corporate debt.2
Finally, the navigation of the interest rate cycle presents a complex dynamic. The BCRP engaged in a prolonged monetary easing cycle, dropping the benchmark rate from a restrictive 7.75% in early 2023 down to 5.00% by the end of 2024.12 Normally, in a traditional banking model, falling rates severely compress net interest margins as asset yields decline faster than deposit costs. Miraculously, Credicorp managed to expand its risk-adjusted NIM to a record 5.55% in Q4 2025 during this easing cycle.6 This defies conventional banking mechanics but is easily explained by two factors: a rapid, aggressive downward repricing of its institutional liabilities, and the deliberate loan mix shift toward high-yielding retail and Yape micro-loans, which possess yields that are highly inelastic to central bank benchmark rate changes. However, as benchmark rates stabilize near an estimated neutral level of 4.5%–5.0% in 2026, the mathematical capacity for further NIM expansion will likely plateau, placing the burden of future earnings growth entirely on absolute volume expansion and non-interest fee income.
7. Management Quality & Corporate Governance
An investment in an emerging market holding company is ultimately an investment in the integrity and competence of its controlling families and executive operators.
Credicorp underwent a meticulously planned, multi-year leadership transition culminating in mid-2024. Gianfranco Ferrari, who previously successfully ran the flagship BCP subsidiary, assumed the Group CEO role in early 2022. In July 2024, Alejandro Perez-Reyes transitioned to the Chief Financial Officer position, and César Ríos moved to the role of Chief Risk Officer. This rotation placed veteran operators with decades of institutional knowledge into the most critical capital allocation and risk management seats, avoiding the disruption often caused by external hires.
The executive team’s track record of execution versus their stated public guidance is highly commendable. During 2023, amidst severe economic contractions and social unrest, management did not capitulate to short-term earnings pressure. They quickly tightened credit risk appetites across the board and aggressively over-provisioned for the anticipated El Niño weather phenomena, taking a S/250 million hit to earnings.12 By 2025, those upfront provisions proved to be overly conservative, allowing the bank to release reserves and driving the reported cost of risk down to a pristine 1.6%.6 Furthermore, the disciplined execution of Yape’s monetization—hitting the critical profitability breakeven point in mid-2024 precisely as forecasted years prior 46—lends immense credibility to their forward-looking financial targets. They are not serial over-promisers.
However, corporate governance requires a highly skeptical evaluation due to the heavy, concentrated nature of insider ownership. The prominent Romero family, led by Executive Chairman of the Board Luis Romero Belismelis, directly controls 12.29% of Credicorp’s outstanding shares. Additionally, Atlantic Security Holding Corporation (ASHC) controls another 15.49% of the voting shares.47
The primary red flag within the governance structure involves related-party transactions. The 2024 Form 20-F details that Credicorp holds a massive S/1.4 billion in direct loans extended to directors, senior management, and their immediate families.47 Furthermore, Credicorp paid approximately US$32 million in 2024 to external suppliers directly related to management or major shareholders (such as Grupo Romero subsidiaries and Hermes Transportes Blindados).47
While the company explicitly states in SEC filings that these transactions occur strictly at standard market rates, without privileged conditions, and are pre-approved by the Board to mitigate conflicts of interest 47, related-party transactions of this magnitude in Latin American family-controlled conglomerates always introduce the latent risk of value extraction. That said, the historic 14.1% annualized TSR generated since 1995 42 serves as empirical, unassailable proof that the Romero family’s financial interests remain broadly aligned with minority public shareholders. They have historically utilized their control to compound equity capital rather than systematically plunder it.
8. Valuation Analysis
Evaluating a dominant financial institution requires analyzing the spread between its generated Return on Equity and its theoretical Cost of Equity, and determining what specific multiple the public market assigns to its tangible book value.
As of early 2026, Credicorp trades at a trailing P/E of approximately 14.3x and a Price-to-Book (P/B) multiple of 2.1x.3
To ascertain if this valuation is justified, a rigorous comparison against domestic and regional peers is required.
| Institution | Country | ROE (2025/LTM) | P/E Ratio | P/B Ratio | Market Position |
| Credicorp (BAP) | Peru | 19.0% | 14.3x | 2.1x | Dominant (34.5% loans) |
| BBVA Peru | Peru | 17.9% | 10.9x | 1.9x | Strong (#2, 21.8% loans) |
| Intercorp (IFS) | Peru | 16.8% | 9.2x | 1.4x | Moderate (#4, retail focus) |
| Itaú Unibanco | Brazil | ~21.0% | 8.6x | 1.8x | Dominant (Brazil) |
| Santander Chile | Chile | ~15.0% | 13.7x | 3.1x | Dominant (Chile) |
(Data derived from 3)
The empirical data illustrates that Credicorp commands a material premium multiple compared to local Peruvian peers (Intercorp and BBVA) and even trades at a premium to the highly profitable regional powerhouse Itaú Unibanco in Brazil. This premium valuation is primarily justified by two distinct variables the market is pricing in:
- The “Yape” Venture Premium: Investors are effectively embedding a venture-capital-like premium into the traditional bank holding company, betting heavily on Yape’s potential to entirely dominate the Peruvian digital economy and eventually scale as a standalone, highly profitable fintech entity.
- Absolute Oligopoly Dominance: BCP’s 34.5% market share and near-monopoly on corporate payroll deposits create a structural earnings resilience that smaller peers simply lack.
Applying a standard residual income valuation framework provides a sober reality check. The theoretical formula is:
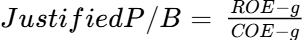
Assuming Credicorp executes perfectly and hits its sustainable target ROE of 19.5% 9, utilizing a Cost of Equity (COE) of 13.0% (which adequately accounts for the Peruvian sovereign risk premium and regional volatility), and assuming a long-term terminal growth rate (g) of 5.0%:
Currently trading at 2.1x Book Value, BAP appears approximately 10% to 15% overvalued based strictly on the discounting of traditional, mature banking cash flows. To mathematically justify a 2.1x P/B multiple, the market is implicitly assuming either a dramatically lower Cost of Equity (implying the total evaporation of Peruvian political risk, which is highly unlikely) or a much higher terminal growth rate fueled entirely by the zero-marginal-cost scaling of Yape’s digital lending ecosystem. The current valuation is undeniably priced for operational perfection; there is absolutely no margin of safety embedded in the stock price for an earnings miss, a failure to rein in OpEx, or a severe macroeconomic shock.
- Upside Scenario: Yape successfully scales its B2B enterprise services and insurance cross-selling, driving the consolidated group ROE to 21%+ while the efficiency ratio compresses rapidly to the promised 42%. The P/B multiple expands toward 2.4x.
- Downside Scenario: Operating expenses remain sticky and elevated, Yape’s unseasoned digital loan cohorts default en masse amid a 2026 election-induced political shock, and ROE reverts to 15%. The stock permanently re-rates to 1.5x P/B, resulting in a severe ~30% capital loss for investors buying at current levels.
9. Risks & Concerns
A critical investment analyst must index heavily on what can permanently impair capital. The risks for Credicorp are severe and binary.
1. Severe Geographic and Political Concentration
Despite minor, value-dilutive offshore acquisitions in Colombia and the US, Credicorp is inherently a highly levered macroeconomic play on the Republic of Peru. The looming April 2026 general election poses a severe tail risk. A victory by a radical populist faction could swiftly introduce devastating price controls on banking interest rates, authorize the total liquidation of the private pension system, or enact punitive, windfall banking taxes targeting BCP’s outsized profitability.
2. Asset Quality Deterioration in Algorithmic Digital Lending Lending incredibly constituted 23% of Yape’s Q4 2025 revenue.6 AI-driven alternative data underwriting models perform exceptionally well during periods of economic expansion and rising employment. However, these proprietary models have never been stress-tested through a deep, prolonged recession. If the Peruvian informal economy contracts sharply, the default correlation among Yape’s 4.1 million micro-borrowers could trigger a rapid, uncontrollable spike in provisioning requirements, instantly destroying the high-ROE digital thesis.
3. Execution Risk on Operational Efficiency Management has repeatedly promised investors a clear glide path to a 42% cost-to-income efficiency ratio.9 Yet, year after year, heavy, required investments in IT infrastructure, cloud computing, and digital engineering headcount keep the ratio elevated (hitting 46.6% in 2025).6 If revenues from these new disruptive initiatives unexpectedly stall, the massive fixed overhead of these technological investments will ruthlessly crush consolidated operating margins.
4. The Regional Drag of Mibanco Colombia Mibanco Colombia’s persistent negative returns (-2.0% ROE) 13 continually siphon precious equity capital and executive management attention away from the highly profitable Peruvian core. If management refuses to cut their losses and exit the Colombian market, it indicates a dangerous failure in capital allocation discipline.
10. Quality of Evidence Assessment
As an objective analyst, it is absolutely imperative to rigorously separate empirical, audited data from optimistic management narratives and broader market speculation.
- Hard, Verifiable Data: The 19.0% consolidated ROE, the declining 4.5% NPL ratio, the staggering 15.9 million MAUs engaging with Yape, and the incredibly low 2.3% cost of deposit funding are audited, verifiable facts.6 They definitively prove the existence of a massive, structural competitive advantage operating today.
- Management Claims (Require Skepticism): The bold projection that the innovation portfolio will reach 10% of total revenue by 2026 32, and the firm guidance of the efficiency ratio compressing down to 42% 43, are purely optimistic internal forecasts. The empirical evidence supporting the 42% efficiency ratio is currently weak, given the massive 12% OpEx growth actually recorded in 2025.6
- Analyst Speculation: The rationale that the $180 million Helm Bank USA acquisition is purely a defensive, synergistic hedge against Latin American capital flight is an analytical deduction based on regional macro dynamics and the exorbitant premium valuation paid 14, rather than an explicit, recorded admission by Credicorp management.
Key Financial Metrics (10-Year Summary & 2025 Snapshot)
| Metric | 2016 | 2018 | 2020 (COVID) | 2022 | 2024 | 2025 |
| Net Income (USD Millions) | $1,041 | $1,212 | $99 | $1,196 | $1,466 | ~$1,800 |
| Return on Equity (ROE) | 18.5% | 17.2% | 1.4% | 17.0% | 16.5% | 19.0% |
| Net Interest Margin (NIM) | N/A | N/A | N/A | ~5.5% | 6.29% | 6.62% |
| Efficiency Ratio | N/A | N/A | N/A | N/A | 45.8% | 46.6% |
| Cost of Risk | N/A | N/A | N/A | N/A | 2.4% | 1.6% |
| NPL Ratio | N/A | N/A | N/A | N/A | 5.3% | 4.5% |
(Data derived from official filings and reports 6)
Final Conclusion:
Credicorp Ltd. is not merely a bank; it is the financial infrastructure of Peru. It possesses a virtually insurmountable economic moat rooted in low-cost deposit generation and unparalleled transactional network density. The successful transformation of Yape into a highly profitable lending engine definitively proves that legacy management can self-disrupt and execute complex technological pivots. However, at a demanding valuation of 2.1x tangible book value, the public market has fully priced in the flawless continuation of 19%+ ROEs and the frictionless, perpetual scaling of digital lending. While it remains a phenomenal business generating massive excess returns on capital, investors allocating at these prices must accept the severe embedded volatility of the Andean political landscape and strictly monitor operating expenses to ensure management actually delivers on their elusive efficiency promises.
Frequently Asked Questions
General Questions
- Thoughtful questions from other investors: During the Q4 2025 earnings call, analysts probed management on how they plan to achieve 8.5% loan growth when Peru’s GDP is only growing at 3.5%. Analysts also questioned the specific negative impacts of Bolivian currency devaluation on the consolidated loan book, the sustainability of the mid-to-high 6% Net Interest Margin (NIM), and how the rapid expansion of Yape’s algorithmic credit portfolio might alter the bank’s cost of risk.
Cyclicality & Earnings Nature
- Cyclical high or low: Earnings are currently at a cyclical high. For the full year 2025, Credicorp reported record net income of S/6,925.4 million ($1.8 billion), a 25.9% year-over-year increase.
- External vs. Internal drivers: Management heavily promotes a narrative that earnings are driven by internal actions, specifically citing a “decoupling” strategy driven by Yape’s digital monetization and a shift toward higher-yielding retail loans. However, the evidence shows they were materially aided by favorable external conditions in 2025, including a 3.5% Peruvian GDP expansion fueled by record copper/gold export prices and massive liquidity injections from government-approved early pension fund withdrawals.
- Revenue stability: Revenues are highly stable due to a dominant, low-cost deposit franchise. Low-cost demand and savings accounts represented 73.0% of total deposits in Q4 2025, resulting in a blended funding cost of just 2.3%.
- Market outlook and TAM: The primary market is domestic (Peru) and it is structurally underpenetrated. Peru’s historical banking penetration (gross loans to GDP) sits around 40%, far below developed market standards, providing a long runway for organic growth.
Business Quality & Competitive Moat
- Industry competitiveness: The traditional banking sector is a highly stable oligopoly, with the top four banks controlling over 80% of market share. However, the digital payments sub-sector is intensely competitive, primarily a duopoly between Credicorp’s Yape and the consortium-backed Plin.
- Profitability (ROE/ROA): Profitability is elite. In 2025, Credicorp generated a consolidated ROE of 19.0%. The flagship universal banking subsidiary, BCP Stand-alone, generated an exceptional full-year ROE of 24.7%. The group’s trailing ROA sits near 2.62%.
- Competitor profitability: Competitors are profitable, but trail Credicorp. BBVA Peru reported a 17.9% ROE for 9M 2025 , and Interbank reported a 16.8% ROE for 2025.
- Barriers to entry and switching costs: Barriers to entry are massive, rooted in physical distribution density and strict Basel III regulatory capital requirements phasing in through 2027. Switching costs are high in corporate banking due to payroll integration, and are increasing in retail as Yape transitions into a “Super App” embedding payments, lending, and insurance.
Financial Condition & Balance Sheet
- Unrecognized assets & off-balance sheet liabilities: The primary unrecognized asset is Yape’s network effect, which boasts 15.9 million monthly active users conducting an average of 66 transactions per month. Off-balance sheet liabilities consist of standard banking items: financial guarantees, stand-by letters, performance bonds, and trade letters of credit.
- Accounting conservatism: Management exhibits conservative provisioning. In 2023, they took a proactive S/250 million charge anticipating severe El Niño damage, which proved overly cautious and allowed for subsequent reserve releases in 2024 and 2025. The NPL coverage ratio is highly robust at 112.4%.
- CapEx / OpEx intensity: The business is becoming highly OpEx intensive as it digitizes. Operating expenses surged 12.0% in 2025, driven by a nearly 18.4% increase in innovation portfolio spending. Consequently, the efficiency ratio remains elevated at 46.6%.
Capital Allocation & Management
- Free cash flow & capital return: The business generates high returns on capital and returns excess cash to shareholders. Management’s policy targets an increasing ordinary dividend, typically paying out 40% to 50% of net income. The 2025 dividend was $11.01 per share, yielding over 3.0%. Share buybacks are immaterial.
- Recent acquisitions: In December 2025, Credicorp announced the acquisition of Helm Bank USA (a Florida community bank) for $180 million. The strategic rationale is to capture offshore wealth management flows and service cross-border LatAm clients.
- Management motivations: Management compensation is tied to long-term profitability and efficiency metrics. Their stated midterm targets are to sustain a 19.5% ROE while driving the elevated cost-to-income efficiency ratio down to 42%.
Valuation & Market Data
- Listing structure: BAP is not an ADR. It is a direct listing on the NYSE of a holding company incorporated in Bermuda.
- Net income vs. cash flow divergence: Operating cash flows diverge significantly from net income due to standard banking activities (changes in the loan book, trading assets, and deposit inflows). For example, in 2024, net income was S/5,501 million while operating cash flow was recorded at S/1,236 million.
Risks & Downside
- Factors causing stock decline: The stock is vulnerable to execution misses priced into its premium valuation. Following the Q4 2025 earnings release, shares fell approximately 2.4% because EPS of $5.93 and revenue of $1.58 billion both missed consensus estimates.
- Catastrophic risk: The insurance arm (Grupo Pacifico) is exposed to severe earthquake risks in Peru. However, this is heavily mitigated through historical excess-of-loss and automatic quota share reinsurance contracts.
- Total loss probability: Exceedingly low. Credicorp is a systemically important institution operating in a sovereign with low public debt and abundant international reserves (approx. 27% of GDP). The bank is also highly overcapitalized, with a BCP CET1 ratio of 13.99%.
Recent News & Events
- Business environment changes: The Peruvian macro environment stabilized significantly in 2025, with GDP recovering to 3.5% and inflation cooling, allowing the central bank to ease rates down to 5.00%.
- New markets/facilities: Credicorp’s digital wallet in Chile, Tenpo, received a formal banking license in January 2026, officially becoming the country’s first neobank.
- Accounting policy changes: The company recently implemented IFRS 17 for insurance contracts, which required the restatement of historical insurance revenues and modified the calculation methodology for the consolidated efficiency ratio.
Works cited
- Credicorp Announces Filing Form 20-F 2024, accessed February 25, 2026, https://credicorp.gcs-web.com/news-releases/news-release-details/credicorp-ltd-credicorp-announces-filing-form-20-f-2024
- credit ratings, research, and data for global capital markets – Moody’s, accessed February 25, 2026, https://www.moodys.com/search-results/all?keyword=peru&searchfrom=GS
- Credicorp (BAP) P/E Ratio: Current & Historical Analysis, accessed February 25, 2026, https://public.com/stocks/bap/pe-ratio
- Credicorp (BAP) Financial Ratios – Investing.com NG, accessed February 25, 2026, https://ng.investing.com/equities/credicorp-ltd-ratios
- What is Competitive Landscape of Credicorp Company?, accessed February 25, 2026, https://portersfiveforce.com/blogs/competitors/credicorp
- Credicorp 2025 profit jumps, ROE hits 19% | BAP SEC Filing, accessed February 25, 2026, https://www.stocktitan.net/sec-filings/BAP/6-k-credicorp-ltd-current-report-foreign-issuer-708fd4055a43.html
- BAP Investor Relations – Credicorp Ltd – Alpha Spread, accessed February 25, 2026, https://www.alphaspread.com/security/nyse/bap/investor-relations
- Credicorp Q4 2025 slides: earnings miss overshadows solid yearly, accessed February 25, 2026, https://www.investing.com/news/company-news/credicorp-q4-2025-slides-earnings-miss-overshadows-solid-yearly-performance-93CH-4506106
- Credicorp Q4 2025 Earnings Report – MarketBeat, accessed February 25, 2026, https://www.marketbeat.com/earnings/reports/2026-2-17-credicorp-ltd-stock/
- BAP – Credicorp Ltd Earnings Call Transcripts | Morningstar, accessed February 25, 2026, https://www.morningstar.com/stocks/xnys/bap/earnings-transcript
- Annual and Sustainability Report – Form 6-K, accessed February 25, 2026, https://www.publicnow.com/view/8D3E44619F4C27300460BD17CB3C57D596A1561A
- CREDICORP (BAP) Q4 2023 Earnings Call Transcript | Fintool, accessed February 25, 2026, https://fintool.com/app/research/companies/BAP/documents/transcripts/q4-2023
- Annual Report for Fiscal Year Ending December 31, 2024 (Form 20-F), accessed February 25, 2026, https://www.publicnow.com/view/52515C55CD8C55ADD3BF98B4BB3416435118F997?1745621202
- Credicorp’s BCP To Acquire Helm Bank USA For $180 Million, accessed February 25, 2026, https://pulse2.com/credicorps-bcp-to-acquire-helm-bank-usa-for-180-million/
- December 2025, accessed February 25, 2026, https://cdn.aglty.io/scotiabank-peru/PDFs/acerca-de/2025/Scotiabank-Peru-Investor-Presentation-Q3-2025.pdf
- Banking Sector Spreads and Bank Competition in Peru – IMF eLibrary, accessed February 25, 2026, https://www.elibrary.imf.org/downloadpdf/display/book/9781513599748/ch017.pdf
- BBVA Perú, accessed February 25, 2026, https://www.bbva.pe/content/dam/public-web/peru/documents/personas/investor-relations/Investor-Report-3Q_2025-English-Version.pdf
- Banco Internacional del Peru S.A.A. – Interbank, accessed February 25, 2026, https://docs.publicnow.com/viewDoc.aspx?filename=117728\EXT\75615AA56248A99A74F3AF7CEF5A19684A6AC9CB_50DB289345A9D48E2EB534885E52686DE9CFD892.PDF
- Scotiabank Investment Analysis Report, https://drive.google.com/open?id=1yQCa59RiIX8nOdhWcylAUAhJpv3jtBrv6zbdWsTyeYY
- SEC Filing – Credicorp Ltd., accessed February 25, 2026, https://credicorp.gcs-web.com/node/17131/html
- LIQUIDITY AND CREDIT – BCRP, accessed February 25, 2026, https://www.bcrp.gob.pe/eng-docs/Publications/Annual-Reports/2024/annual-report-2024-5.pdf
- Intercorp Financial Services Inc (IFS) Q4 2025 Earnings Call Hig, accessed February 25, 2026, https://www.gurufocus.com/news/8625407/intercorp-financial-services-inc-ifs-q4-2025-earnings-call-highlights-record-net-income-and-strategic-growth-amid-challenges
- Check out our fourth quarter 2024 results | Credicorp, accessed February 25, 2026, https://grupocredicorp.com/en/nearly-5-7-million-people-have-been-financially-included-by-bcp-and-yape-since-2020/
- Argentinian Banking Sector Investment Analysis, https://drive.google.com/open?id=17LbVBukyCiXcbaUNxvky_hTgtiySJ3pSjVW9L4Cc6VM
- Peru: 2025 Article IV Consultation-Press Release; and Staff Report in, accessed February 25, 2026, https://www.elibrary.imf.org/view/journals/002/2025/125/article-A001-en.xml
- Peru Total Loans Growth | 2002 – 2026 | Economic Indicators – CEIC, accessed February 25, 2026, https://www.ceicdata.com/en/indicator/peru/total-loans-growth
- Evolution of bank and non-bank corporate funding in Peru, accessed February 25, 2026, https://bis.org/publ/bppdf/bispap83p.pdf
- Video | The Global Findex Database 2021: Financial Inclusion, accessed February 25, 2026, https://www.worldbank.org/en/news/video/2022/06/29/video-the-global-findex-database-2021-financial-inclusion-digital-payments-and-resilience-in-the-age-of-covid-19
- Measuring Financial Inclusion The Global Findex Database | FDIC, accessed February 25, 2026, https://www.fdic.gov/system/files/2024-08/measuring-financial-inclusion-the-global-findex-database.pdf
- Competition in Mobile Payment Services – Note by Peru – O.N.E, accessed February 25, 2026, https://one.oecd.org/document/DAF/COMP/WD(2025)15/en/pdf
- Peru: 2024 analysis of payments and ecommerce trends, accessed February 25, 2026, https://paymentscmi.com/insights/payments-ecommerce-trends-peru-2024/
- Credicorp Held Investor Day Marking 30 Years on … – Credicorp Ltd., accessed February 25, 2026, https://credicorp.gcs-web.com/news-releases/news-release-details/credicorp-ltd-credicorp-held-investor-day-marking-30-years-nyse
- Implementation status of final Basel III reforms varies across globe, accessed February 25, 2026, https://www.moodys.com/web/en/us/insights/regulatory-news/implementation-status-of-final-basel-iii-reforms-varies-across-globe.html
- Credicorp Net Income 2012-2025 | BAP | MacroTrends, accessed February 25, 2026, https://www.macrotrends.net/stocks/charts/BAP/credicorp/net-income
- Credicorp Ltd. (BAP) Q2 2025 Earnings Call Transcript, accessed February 25, 2026, https://seekingalpha.com/article/4814172-credicorp-ltd-bap-q2-2025-earnings-call-transcript
- Credicorp’s Tenpo Wins Chile Neobank License What It Means For, accessed February 25, 2026, https://www.sahmcapital.com/news/content/credicorps-tenpo-wins-chile-neobank-license-what-it-means-for-growth-2026-01-21
- Dividend History | Credicorp, accessed February 25, 2026, https://credicorp.gcs-web.com/stock-information/dividend-history
- Credicorp (NYSE:BAP) Dividend Yield, History and Growth, accessed February 25, 2026, https://simplywall.st/stocks/us/banks/nyse-bap/credicorp/dividend
- BAP: Dividend Date & History for Credicorp Ltd – Dividend.com, accessed February 25, 2026, https://www.dividend.com/stocks/financials/banking/banks/bap-credicorp-ltd/
- Credicorp (BVL:BAP) – Earnings & Revenue Performance, accessed February 25, 2026, https://simplywall.st/stocks/pe/banks/bvl-bap/credicorp-shares/past
- Credicorp’s BCP subsidiary to acquire Helm Bank USA for $180, accessed February 25, 2026, https://www.investing.com/news/company-news/credicorps-bcp-subsidiary-to-acquire-helm-bank-usa-for-180-million-93CH-4424694
- credicorp ltd. – SEC.gov, accessed February 25, 2026, https://www.sec.gov/Archives/edgar/data/1001290/000114036125037765/ef20056796_6k.htm
- Credicorp Holds Investor Day; Targets 19.5% ROE, C/I – Stock Titan, accessed February 25, 2026, https://www.stocktitan.net/news/BAP/credicorp-ltd-credicorp-held-investor-day-marking-30-years-on-nyse-jj701zuu5wkv.html
- Credicorp Ltd (BAP) Q4 2025 Earnings Call Highlights: Record Hig, accessed February 25, 2026, https://www.gurufocus.com/news/8616404/credicorp-ltd-bap-q4-2025-earnings-call-highlights-record-high-net-income-and-strategic-growth-initiatives
- Peru – Economic Outlook – BBVA Research, accessed February 25, 2026, https://www.bbvaresearch.com/wp-content/uploads/2025/10/Peru-Economic-Outlook-September-2025.pdf
- Credicorp Highlights Growth Initiatives Driven by Innovation Strategy, accessed February 25, 2026, https://credicorp.gcs-web.com/news-releases/news-release-details/crediciorp-ltd-credicorp-highlights-growth-initiatives-driven
- www.sec.gov, accessed February 25, 2026, https://www.sec.gov/Archives/edgar/data/1001290/000114036125026765/ef20052287_20fa.htm
- Banco Safra – Latam Financials – 101325 | PDF – Scribd, accessed February 25, 2026, https://www.scribd.com/document/932656618/Banco-Safra-Latam-Financials-101325
- Intercorp Financial Services Inc Compare against Competitors, accessed February 25, 2026, https://za.investing.com/pro/BVL:IFS/compare/BVL:BAP,BVL:INTERBC1,BVL:BBVA,BOVESPA:BBDC3,TSX:NA,SNSE:BSANTANDER
- Credicorp ROE – Return on Equity 2012-2025 | BAP – Macrotrends, accessed February 25, 2026, https://www.macrotrends.net/stocks/charts/BAP/credicorp/roe
- SEC Filing – Credicorp Ltd., accessed February 25, 2026, https://credicorp.gcs-web.com/node/18671/html