
I. INDUSTRY STRUCTURE AND DYNAMICS
To accurately evaluate BNP Paribas SA as a long-term equity investment, the analysis must be anchored in a rigorous deconstruction of the structural characteristics of the European universal banking industry. The fundamental architecture of the European financial sector dictates the absolute ceiling on the returns that any single institution can generate.
The European banking sector operates under a fundamentally different paradigm compared to its United States counterparts, characterized by acute structural overcapacity, regulatory fragmentation, and an incomplete macroeconomic union. The United States banking sector is defined by a distinct structural dichotomy: it is highly fragmented at the bottom, populated by thousands of small community banks, yet functions as a rigid, top-heavy oligopoly at the apex, where the four largest universal banks—JPMorgan Chase, Bank of America, Wells Fargo, and Citigroup—control a massive and disproportionate share of domestic deposits and capital markets activity.1 This concentration in the U.S. generates immense economies of scale.
Conversely, the competitive landscape in Europe remains heavily fragmented along national borders, effectively denying pan-European banks the oligopolistic pricing power enjoyed by their American peers. BNP Paribas competes against a cohort of entrenched national champions. In its home market of France, it battles cooperative giants like Crédit Agricole and Groupe BPCE, alongside traditional rival Société Générale.2 In Germany, it faces Deutsche Bank and Commerzbank; in the UK, HSBC and Barclays; in Italy, Intesa Sanpaolo and UniCredit; and across the Benelux region, ING.2 Despite years of supposed consolidation, the structural overcapacity is staggering: as of 2024, there were still 4,834 credit institutions operating within the European Union, managing €45.1 trillion in assets through nearly 127,000 physical branches.6 This persistent overbanking structurally depresses net interest margins and fee pricing across the continent, leading to chronically lower returns on unlevered equity compared to the U.S. market.
The fundamental economics of European banking over the past decade have been dictated by the extreme monetary policy of the European Central Bank (ECB). Banking is, at its core, a commoditized spread business: financial institutions purchase raw material in the form of deposits and sell finished goods in the form of loans.1 Between 2014 and 2022, the ECB enforced a negative interest rate policy (NIRP) that severely impaired this traditional economic model.8 During this period, the excess liquidity of euro area banks increased from €120 billion to more than €4.5 trillion.8 Because banks were essentially forced to pay the central bank to hold this excess liquidity, and intense domestic competition prevented them from passing negative rates onto retail depositors, profitability was structurally crushed.
This macroeconomic environment shifted violently in the summer of 2022. The ECB’s aggressive rate hiking cycle to combat inflation instantly transformed trillions of euros in excess liquidity into a massive source of risk-free interest income via the ECB’s deposit facility.8 The interest rate that banks could earn rose by a cumulative 4.5 percentage points by late 2023.8 Consequently, European bank profitability surged. However, critical analysis indicates that this margin expansion is proving to be largely cyclical rather than a permanent structural shift. By late 2024 and throughout 2025, the ECB entered a cautious easing cycle, cutting the main refinancing and deposit facility rates to manage stagnant European economic growth and normalizing inflation.10 Simultaneously, deposit betas—the proportion of rate changes banks are forced to pass to customers—accelerated as consumers shifted from non-interest-bearing sight deposits to term deposits and regulated savings.13 If rates decline substantially further, European banks will face renewed margin compression, underscoring the reality that recent peak earnings were artificially subsidized by central bank mechanics.
Regulation serves as the primary structural impediment to capital efficiency in Europe. European banks are burdened by the ongoing implementation of the Basel III finalization (often referred to as Basel IV or the CRR3/CRD VI package). A central tenet of this framework is the “output floor,” which limits the capital relief generated by banks’ internal risk models (IRB) to 72.5% of the standardized approach.15 This mechanically inflates Risk-Weighted Assets (RWA) and depresses reported capital ratios.18 While the EU has phased the implementation through 2032 and recently delayed the Fundamental Review of the Trading Book (FRTB) to 2026/2027 to avoid disadvantaging EU banks against U.S. competitors, the regulatory direction of travel permanently increases the cost of operating a trading and corporate lending balance sheet.15
Furthermore, the European Banking Union remains woefully incomplete. Without a true pan-European deposit insurance scheme, national regulators routinely ring-fence capital and liquidity within domestic subsidiaries to protect national taxpayers. For a universal bank like BNP Paribas, this lack of cross-border waivers traps an estimated €225 billion of capital and €250 billion of liquidity across the sector, nullifying the theoretical economies of scale of operating a pan-European balance sheet.20 The Minimum Requirement for Own Funds and Eligible Liabilities (MREL) in the EU is also significantly higher than in the U.S. (averaging 28% of RWAs versus 22% for U.S. entities), permanently driving up wholesale funding costs.20
Because of these regulatory and political barriers, cross-border M&A—the traditional capitalist remedy for industry overcapacity—remains deeply constrained. While 2024 and 2025 saw a resurgence in banking M&A, primarily driven by banks seeking to deploy excess capital generated during the rate hike cycle, major transactions face fierce political headwinds.21 National governments routinely intervene to block foreign takeovers, utilizing mechanisms like Italy’s “golden power” rules or regulatory resistance in Spain (e.g., the BBVA/Sabadell dynamic) to preserve domestic champions.22 Cross-border banking M&A in Europe is the slowest in the world, taking an average of 285 days compared to 219 days in the U.S..20 Consequently, European consolidation remains largely domestic (extracting local branch synergies), while cross-border activity is restricted to capital-light capability acquisitions, such as wealth and asset management, rather than transformative retail banking mergers.21 BNP Paribas has smartly adapted to this reality, acting as a consolidator of specialized, non-branch assets rather than attempting hostile cross-border retail takeovers.
Finally, the sector faces a confluence of secular headwinds and tailwinds. On the negative side, European demographics are rapidly aging, inherently limiting organic credit demand and loan growth.12 Fintech challengers and digital wallets continue to disintermediate the highly profitable payments value chain, while private credit funds siphon off lucrative middle-market corporate lending.1 Geopolitical fragmentation, particularly the economic decoupling from Russia following the 2022 invasion of Ukraine and rising trade tensions with China and the U.S., threatens the cross-border trade flows that fuel corporate banking revenues.23 Conversely, a major secular tailwind is the massive corporate financing requirement associated with the green energy transition and AI infrastructure build-outs. Furthermore, the slow but necessary advancement of the European Capital Markets Union (CMU) proposals aims to deepen regional capital markets, which would disproportionately benefit scale players with robust capital markets infrastructure like BNP Paribas.12
II. COMPANY OVERVIEW AND COMPETITIVE POSITION
BNP Paribas is the largest bank in the European Union by total assets, managing approximately €2.8 to €2.9 trillion.4 The Group operates through a highly diversified, integrated universal banking model structured into three core operating divisions: Corporate & Institutional Banking (CIB), Commercial, Personal Banking & Services (CPBS), and Investment & Protection Services (IPS).
A detailed breakdown of these segments reveals the true drivers of the firm’s profitability. In 2025, the Group generated a total of €51.2 billion in revenues and €17.06 billion in pre-tax income.27
- Corporate & Institutional Banking (CIB): This segment is the global engine of the franchise. In 2025, CIB generated €18.99 billion in revenue, representing roughly 37% of Group revenues, and contributed approximately 32% to the Group’s pre-tax profit allocation.27 It operates a capital-efficient “Originate to Distribute” model encompassing Global Banking, Global Markets, and Securities Services.
- Commercial, Personal Banking & Services (CPBS): The traditional heart of the bank, encompassing domestic retail networks in France, Belgium, Italy, and Luxembourg, alongside specialized businesses like Arval (vehicle leasing) and Personal Finance. CPBS generated €26.71 billion in revenue in 2025, constituting 52% of total group revenue and roughly 54% of pre-tax profit.27
- Investment & Protection Services (IPS): The high-margin, capital-light wealth, asset management, and insurance (Cardif) arm. IPS generated €7.23 billion in 2025 revenues, representing roughly 14% of the group’s total revenue and pre-tax profit, a figure set to grow significantly following the consolidation of AXA IM.27
Analyzing BNP Paribas through the strict framework of competitive advantage reveals a nuanced reality. Does BNP possess a durable economic moat, or is it merely surviving on the inertia of its immense scale?
The bank’s primary competitive advantage—and perhaps its only true structural moat—is its scale and scope in Corporate & Institutional Banking. In a highly regulated, post-GFC environment, fixed compliance and technology costs are astronomical. In 2024, the world’s 12 largest investment banks spent a combined $34 billion on technology.30 BNP Paribas leverages its massive balance sheet to fund an expansive technological transformation, deploying over 800 artificial intelligence use cases in production by 2024 to automate compliance, risk management, and pricing, with an aim to generate €750 million in value by 2026.24 This scale allows BNP to act as a comprehensive one-stop-shop for multinational corporations requiring complex cross-border cash management, foreign exchange, and capital markets access.31 The friction involved for a corporate treasurer to untangle global cash pooling and trade finance facilities creates massive switching costs. Furthermore, BNP benefits from network effects in its global trade finance and transaction banking divisions; its presence in over 60 countries means it can clear and settle transactions internally across borders, a capability smaller regional banks simply cannot replicate.4
However, in retail banking (CPBS), BNP’s moat is severely compromised by local market mechanics and structurally weak unit economics. A critical analysis of its key markets demonstrates these vulnerabilities:
France (Home Market): While BNP Paribas is the largest bank in Europe by assets, in its home market of France, it actually trails the cooperative giant Crédit Agricole in total domestic retail market share.3 More importantly, the French retail banking market is structurally toxic for generating high returns on equity. French bank profitability is artificially suppressed by state-regulated “Livret A” savings accounts and a mortgage market heavily dominated by fixed-rate loans governed by strict usury laws (taux d’usure).13 When the ECB raised rates in 2022 and 2023, French banks were politically and legally forced to pay higher yields on regulated deposits immediately, while their legacy fixed-rate mortgage assets yielded minimal returns, severely compressing Net Interest Margins (NIM).13 Consequently, French retail revenue recovery has severely lagged the rest of Europe; while Italian and Spanish banks posted record profits, French retail net interest income remained sluggish through 2024, only beginning to meaningfully rebound in the second half of 2025.13
Belgium (BNP Paribas Fortis): Acquired during the absolute depths of the 2008-2009 financial crisis, Fortis was a masterstroke of distressed capital allocation.35 Today, BNP Paribas Fortis is the undisputed market leader in Belgium, a highly concentrated and rational banking market. In 2024, it delivered €2.9 billion in net profit on €153 billion of loans and €156 billion in deposits.37 Belgian retail banking is a genuinely good business, and Fortis functions as a highly cash-generative cash cow for the broader Group, subsidizing weaker divisions.
Italy (BNL): The 2006 acquisition of Banca Nazionale del Lavoro (BNL) has historically been a severe drag on group returns. Plagued by high operating costs and elevated non-performing loans relative to elite domestic competitors, BNL has struggled to earn its cost of capital. A comparison with Intesa Sanpaolo highlights this disparity: while Intesa targets a gross NPE ratio of just 1.6% by 2025 and operates with an annualized cost of risk of just 25 basis points 38, BNL’s cost of risk stood at a heavily elevated 138 basis points on outstanding loans in Q3 2025.41 BNL lacks the impregnable competitive position in Italy that Fortis enjoys in Belgium, making it a structurally mediocre asset.
U.S. Operations: Recognizing its sub-scale position in U.S. retail banking—where it lacked the density to compete with the technology budgets of JPMorgan or Bank of America—management executed a brilliant strategic retreat. BNP sold Bank of the West to BMO in 2023 for $16.3 billion, securing a premium multiple right before the March 2023 U.S. regional banking crisis.42 This unlocked €7.6 billion in capital for redeployment.43 Crucially, BNP retained its U.S. CIB operations, operating a capital-light advisory and global markets franchise that acts as a vital conduit for European corporates operating in the Americas. This ensures BNP remains a global competitor without the dead weight of a sub-scale foreign retail network.
CIB Globally: In global investment banking, BNP is a genuine top-tier competitor, repeatedly capturing market share from retreating European peers like Credit Suisse and Deutsche Bank. Coalition Greenwich data confirms BNP’s status as the #1 Global Banking platform in EMEA, #1 in EMEA syndicated loans, and a top 4 player globally in Transaction Banking.31 The bank’s Global Markets division is highly competitive in FICC and Equity Derivatives, capitalizing on the 2024-2025 surge in equities trading and global macroeconomic volatility.45
Evaluating BNP’s cost efficiency, the bank has historically been burdened by the high cost base endemic to French banking, where rigid labor laws, high severance costs, and expansive physical branch networks elevate the cost-to-income (C/I) ratio.48 Ten years ago, BNP’s C/I ratio routinely sat in the high 60s, severely lagging the mid-50s ratios of elite global peers. However, aggressive restructuring, digitalization, and the closure of redundant real estate have driven structural improvements. In 2024, the Group’s C/I ratio improved to 61.8%, and further decreased to 61.2% by the end of 2025.27 Management generated €800 million in operating efficiency savings in 2025 alone, exceeding their target and pushing toward a cumulative €3.5 billion in savings for the 2022-2026 period.27 Management has set a highly aggressive target to drive the C/I ratio below 56% by 2028 via a new structural transformation plan for support functions.28 While impressive, achieving a 56% ratio in a universal banking model with heavily regulated European labor forces will require flawless execution and massive AI-driven automation.
III. FINANCIAL PERFORMANCE AND RETURNS
A rigorous, objective analysis of BNP Paribas’s financial trajectory over the past decade reveals a dramatic transition. For much of the post-2008 decade, burdened by zero interest rates, non-performing legacy loans, and spiraling compliance costs, BNP Paribas generated Returns on Tangible Equity (ROTE) hovering between 7% and 9%. Given that the standard banking cost of equity sits between 10% and 12%, the bank systematically destroyed economic value with every retained euro, entirely justifying its persistent and severe discount to tangible book value.
This value-destroying paradigm shifted dynamically following the 2022 ECB rate hikes, the shedding of low-returning assets, and the successful execution of the “GTS 2025” strategic plan.
10-Year Financial Summary & Trend Analysis
| Fiscal Year | Revenues (€bn) | Pre-Tax Income (€bn) | Net Income (€bn) | EPS (€) | ROTE (%) | Cost of Risk (bps) | CET1 Ratio (%) | Cost/Income (%) |
| 2015 | 42.9 | 10.3 | 6.7 | 5.14 | ~9.2% | 51 | 10.9% | 68.2% |
| 2016 | 43.4 | 11.2 | 7.7 | 6.00 | 9.3% | 46 | 11.5% | 67.5% |
| 2017 | 43.1 | 11.3 | 7.7 | 6.05 | 8.9% | 39 | 11.8% | 67.8% |
| 2018 | 42.5 | 10.1 | 7.5 | 5.73 | 8.8% | 35 | 11.8% | 72.1% |
| 2019 | 44.5 | 11.3 | 8.1 | 6.21 | 10.0% | 39 | 12.1% | 71.3% |
| 2020 | 44.2 | 9.8 | 7.0 | 5.31 | 7.6% | 66 | 12.8% | 71.6% |
| 2021 | 46.2 | 13.6 | 9.4 | 7.26 | 10.0% | 34 | 12.9% | 67.7% |
| 2022 | 50.4 | 14.3 | 10.1 | 7.80 | 11.4% | 31 | 12.3% | 66.1% |
| 2023 | 46.9 | 14.9 | 11.2 | 9.21 | ~10.2% | 32 | 13.2% | 63.0% |
| 2024 | 48.8 | 16.1 | 11.7 | 9.57 | 10.9% | 33 | 12.9% | 61.8% |
| 2025 | 51.2 | 17.0 | 12.2 | 10.29 | 11.6% | 34 | 12.6% | 61.2% |
(Data compiled from official BNP Paribas earnings materials, Universal Registration Documents, and financial data aggregators. Note: EPS figures are adjusted for currency and restatements where applicable; 2023-2025 data reflects distributable bases and IFRS 17 restatements.3)
The 2025 results underscore the bank’s renewed earnings power. Revenues reached a record €51.22 billion (up 4.9% YoY), driving net income to €12.22 billion (up 4.6% YoY) and pushing EPS to €10.29.27 Crucially, the bank achieved a ROTE of 11.6% in 2025, successfully crossing the threshold of its estimated 10-11% cost of equity.27 This was achieved through persistent operational leverage, posting a positive “jaws effect” (revenues growing faster than costs) of 1.0 point for the year, and 2.9 points in the fourth quarter alone.27
Revenue Quality and Durability: BNP’s revenue quality is highly diversified, acting as an internal hedge against macroeconomic cycle volatility. Unlike pure-play investment banks, BNP is not solely reliant on volatile trading revenues, nor is it entirely dependent on net interest income like regional lenders. In Q4 2025, CPBS contributed roughly 54% to operating performance, CIB contributed 32%, and IPS 14%.28 While CIB trading revenues (Global Markets) are inherently volatile, they are counterbalanced by the highly recurring fee streams of IPS (Asset Management, Wealth Management, Insurance)—which saw a massive 39.6% revenue jump in Q4 2025 following the AXA IM consolidation—and the vast, sticky net interest income base of the commercial banking networks.27
Cost of Risk and Asset Quality:
Perhaps the greatest empirical evidence of BNP’s operational excellence over the past cycle has been its peerless credit risk management. Despite navigating the COVID-19 pandemic (where cost of risk spiked to a highly manageable 66 bps in 2020), the 2022 massive rate shock, and the subsequent European manufacturing stagnation, BNP’s cost of risk has remained exceptionally benign.
In 2024, the cost of risk was just 33 basis points, rising marginally to 34 basis points in 2025, comfortably beating management’s target of keeping it below 40 bps through the cycle.27 As of Q4 2025, the ratio of non-performing loans (NPL) stood at an incredibly low 1.6%, with a strong Stage 3 coverage ratio of 66.9%.27 This superior credit performance is entirely derived from the bank’s highly granular, diversified exposure. BNP does not chase yield in risky tranches; no single corporate sector accounts for more than 4% of total group exposures.54 Furthermore, hidden credit risks that have decimated U.S. regional banks, such as institutional Commercial Real Estate (CRE) exposure, remain tightly contained due to stricter European loan-to-value underwriting standards and less exposure to the severely distressed U.S. office sector.
Balance Sheet Strength: Capital adequacy is robust. The Common Equity Tier 1 (CET1) ratio stood at 12.6% at the end of 2025.27 While this represents a slight decline from 13.2% in 2023, the reduction was driven by the intentional, accretive deployment of capital for strategic acquisitions (AXA IM) and organic RWA growth, as well as the mechanical headwinds of Basel IV implementation (-50 bps impact recognized in early 2025).29 Even at 12.6%, the CET1 ratio remains vastly superior to the ECB’s SREP regulatory requirement of 10.42%.29 Management has explicitly targeted a return to a 13% CET1 ratio by 2027, post-implementation of the final FRTB framework, driven by organic capital generation of roughly 30 bps per quarter.41
Has BNP historically earned its cost of equity? No. Between 2010 and 2020, it was a chronic underperformer on a cost-of-capital basis. However, the structural pivot executed post-2022 indicates that the bank can now sustainably generate 11-12% returns, provided it maintains strict cost discipline and avoids catastrophic credit events during the current ECB easing cycle.
IV. GROWTH HISTORY AND OPPORTUNITIES
Generating organic growth in European banking is notoriously difficult due to the continent’s demographic stagnation and fierce domestic competition. Consequently, BNP Paribas has engineered its growth over the past 15 years through a combination of ruthless market-share capture in CIB and highly opportunistic, counter-cyclical M&A.
Acquisition Track Record: Management’s historical capital deployment into major M&A is bifurcated in its success. The 2006 acquisition of Italy’s BNL was poorly timed ahead of the sovereign debt crisis and struggled to earn its cost of capital for a decade due to toxic NPLs. Conversely, the 2009 acquisition of Fortis Bank (Belgium) was a masterclass in distressed asset purchasing. BNP acquired 75% of Fortis for €14.5 billion—below its pre-crisis book value—during a period of immense liquidity stress.35 By aggressively cutting €500 million in overlapping costs while retaining the strong local brand, BNP stabilized the asset.35 Post-merger, Fortis became a high-ROA engine, driving group net income upward and proving that cross-border M&A can create shareholder value when executed at distressed valuations with clear synergies.
More recently, the 2023 sale of Bank of the West demonstrated management’s disciplined willingness to divest sub-scale, non-strategic assets. Recognizing they lacked the scale to compete in U.S. retail against domestic giants, BNP sold the asset to BMO for $16.3 billion (a premium multiple of 1.7x tangible book), brilliantly timing the exit right before the 2023 U.S. regional banking crisis.42
Strategic Plans and Credibility: Unlike many European bank management teams that perpetually overpromise and underdeliver, BNP Paribas has established strong credibility by meeting the targets of its “GTS 2025” (Growth, Technology, Sustainability) plan. Management promised a ROTE near 12% by 2025, positive jaws effects, and EPS growth above 7%.57 The delivery of an 11.6% ROTE, a +1.0 point jaws effect, and EPS of €10.29 in 2025 definitively validates management’s execution capabilities.27
The AXA IM Acquisition (2025) and Fee-Based Growth: Where can BNP realistically grow from here? With domestic loan growth capped by European GDP, growth must come from capital-light, fee-based businesses. This strategic imperative drove the transformational €5.1 billion acquisition of AXA Investment Managers (AXA IM) from French insurer AXA, completed in July 2025.28
The strategic rationale is highly compelling. The European asset management industry is suffering severe fee compression from passive U.S. index giants (BlackRock, Vanguard). Scale is the only defense. By merging BNP Paribas Asset Management with AXA IM, the bank creates the third-largest European asset manager with over €1.6 trillion in AUM and becomes the European leader in long-term savings.41 This immense scale allows for the amortization of fixed tech and compliance costs over a massive asset base.
From a capital allocation perspective, while the upfront price tag was substantial, the targeted returns are highly accretive. Management projects €550 million in revenue and cost synergies by 2029, targeting an aggressive 18% Return on Invested Capital (RoIC) from the combined entity by 2028, and 22% by 2029.28 Integration risk is the primary concern, as merging disparate IT systems and investment cultures in asset management often leads to key personnel departures and AUM outflows. However, if these integration targets are met, the deal will permanently tilt BNP’s revenue mix toward durable, high-ROE fees, significantly reducing the group’s overall capital intensity.
Furthermore, BNP’s insurance division, Cardif, acts as a massive captive distribution platform. Generating €36.4 billion in gross written premiums in 2024 with €287 billion in AUM, Cardif is highly profitable, with pre-tax net profit rising 13% to €1.6 billion.60 Crucially, Cardif operates an open-architecture partnership model, generating 52% of its premiums with partners outside the BNP Paribas Group (e.g., BCC Iccrea in Italy, Neuflize OBC).60 This proves it is a genuinely competitive standalone business, not merely a captive product-pusher.
Future Growth Vectors (2026-2028):
Building on the GTS 2025 success, management has outlined a highly aggressive 2028 trajectory:
- ROTE Target: >13% (upgraded from a previous 13% target).27
- Net Income CAGR (2025-2028): >10%.27
- Cost-to-Income Ratio: <56% by 2028.27
To achieve this, BNP will rely on:
- CIB Market Share Gains: Continuing to exploit its Originate & Distribute model and tech investments to capture prime brokerage and FICC trading flow from retreating rivals.41
- Specialized Businesses Expansion: Scaling digital banking franchises like Nickel (targeting multi-country scale) and expanding Arval’s highly profitable vehicle leasing fleet.57
- Bolt-on Acquisitions: Utilizing the remaining excess capital from the Bank of the West sale to acquire niche capabilities, such as the 2024 acquisition of HSBC’s private banking activities in Germany to bolster wealth management.26
V. CAPITAL ALLOCATION
Management’s capital allocation is the direct link between business value and shareholder value. Under the leadership of CEO Jean-Laurent Bonnafé, BNP Paribas operates with disciplined, albeit traditionally conservative, capital allocation mechanics that have recently pivoted toward aggressive shareholder return.
Management Quality and Governance: Jean-Laurent Bonnafé has been the CEO of BNP Paribas since 2011, making him one of the longest-tenured and most respected bank executives in Europe.61 An engineer by training, his track record is defined by methodical risk management, the successful navigation of the 2014 sanctions crisis, and the steady digital modernization of the bank. His performance is highly rated by the market. However, governance and succession planning present a moderate risk. In May 2025, shareholders overwhelmingly voted to raise the mandatory retirement age for the CEO, allowing the 63-year-old Bonnafé to potentially remain at the helm until the 2031 annual meeting.62 While this ensures stability during the execution of the 2028 strategic plan, it highlights a lack of an obvious internal successor ready to take the reins, with his top deputies already in their mid-60s.62
Dividends and Payout Policy: The bank maintains a strict and shareholder-friendly distribution policy, returning 60% of earnings to shareholders. This is structured as a minimum 50% cash dividend and 10% in share buybacks.63 The dividend growth track record is exceptional for the sector, boasting a ~10% CAGR since 2008.25 The bank paid €4.79 per share for 2024, and increased this by 7.7% to €5.16 for 2025.27 Furthermore, in 2025, management instituted a semi-annual interim dividend (paying €2.59 in September 2025) to smooth cash flows for institutional investors and mitigate the stock price gaps associated with massive single annual payouts.28
Share Buybacks and Excess Capital: Historically, European banks were paralyzed by regulators and unable to repurchase shares. This constraint has lifted. In November 2025, the ECB authorized BNP to launch a €1.15 billion share buyback program.56
When a bank trades at a steep discount to tangible book value (P/TBV of ~0.60x – 0.65x), repurchasing shares is the single most mathematically accretive action management can take. Every euro spent retiring shares at 60 cents on the dollar instantly boosts the Tangible Book Value Per Share (TBVPS) for remaining owners and structurally increases future EPS and ROTE without taking on an ounce of additional credit risk.
Crucially, management has announced a structural shift in how it handles excess capital. The bank has set a firm CET1 ratio target of 13% by 2027 (post-FRTB implementation). Starting in 2027, the share of excess capital above this 13% threshold will be determined and redistributed to shareholders annually.27 This is a highly bullish signal that buyback velocity will accelerate if the stock remains undervalued, shifting BNP from a pure dividend-yield play to a total-return compounder. With organic capital generation running at roughly 30 bps per quarter, the bank has immense capacity to fund both organic loan growth (~2% RWA growth per year) and massive shareholder returns.41
VI. RISKS AND HEADWINDS
Despite structural improvements and exceptional credit metrics, investing in BNP Paribas carries profound risks inherent to the European macroeconomic and regulatory landscape. A critical analyst must weigh the following threats:
1. Regulatory and Political Risk: European banks are functionally treated as quasi-utilities governed by hostile regulatory regimes. The impending implementation of Basel IV (CRR3) and the Fundamental Review of the Trading Book (FRTB)—delayed in the EU to 2026/2027—will mechanically inflate Risk-Weighted Assets (RWA) and suppress capital ratios, limiting lending capacity.15 Furthermore, European governments facing severe fiscal deficits frequently target banks with windfall taxes or increased levies (as seen recently in Spain and Italy), acting as a permanent, unpredictable cap on shareholder returns.
2. Macroeconomic Risk and Rate Sensitivity: The Eurozone borders on structural stagnation. Germany’s industrial model is challenged, and French fiscal policy remains highly volatile. BNP’s recent 11.6% ROTE was heavily subsidized by the ECB’s high-rate environment. If the ECB is forced to aggressively slash rates back toward zero to combat a deep recession, BNP’s CPBS net interest margin will compress rapidly as asset yields reprice lower.14 While credit quality is pristine today (1.6% NPL), a severe European recession paired with a commercial real estate downturn could force provisioning significantly higher than the current benign 34 bps run-rate.27
3. Geopolitical and Trade Risk: BNP’s global CIB franchise is highly exposed to the fragmentation of global trade. The implementation of aggressive U.S. tariffs under the incoming administration, escalating tensions involving China, or a widening of the Russia/Ukraine conflict could freeze cross-border capital flows. This would significantly dampen the lucrative M&A advisory, trade finance, and global markets transaction pipelines that fueled the 2024 and 2025 revenue beats.12
4. Litigation and Compliance Risk: In 2014, BNP Paribas paid a devastating $8.9 billion fine to U.S. authorities for violating sanctions against Sudan, Cuba, and Iran. While the bank’s compliance culture has been radically overhauled—now operating as a massive, AI-augmented fortress with strict KYC and AML frameworks—the memory of this existential threat lingers.24 In modern global banking, a single severe regulatory failure or compliance breach can wipe out a full year of net income. The sheer geographic footprint of BNP across 64 countries ensures that operational and compliance risk remains permanently elevated.4
5. Competition Risk: U.S. universal banks operate with structurally higher ROEs, giving them a vastly superior currency (their highly-valued stock) to deploy in global talent acquisition and technology investment. Meanwhile, agile fintechs (like Revolut or Adyen) and private credit giants (like Apollo or Blackstone) continue to disintermediate the most profitable segments of European finance without bearing the regulatory capital burden of a traditional bank.1
The Bear Case Steel-Man:
The ultimate bear case argues that BNP Paribas is a structurally mediocre business trapped in a structurally dying continent. Bears argue that the 11.6% ROTE achieved in 2025 is absolute peak-cycle—artificially inflated by the ECB’s rate hikes and a massive, unsustainable boom in equities trading. As rates fall, French retail margins will remain sluggish due to regulated Livret A deposits, while CIB revenues normalize downward. Furthermore, bears argue that the promised <56% cost-to-income ratio is a fantasy in a country with rigid labor laws, and that Basel IV RWA inflation will permanently cap the CET1 ratio, preventing meaningful buybacks. In this scenario, normalized ROTE reverts below 9%, and the bank remains a permanent value trap, destroying economic value while trading endlessly at 0.6x book value.
VII. VALUATION
Valuation is where the bull and bear arguments violently collide. As of early 2026, BNP Paribas trades at approximately €54 to €59 per share (dependent on ADR vs Euronext pricing variations), against a Q1 2025 reported Tangible Book Value Per Share (TBVPS) of €95.80.29
This pricing places BNP’s Price-to-Tangible Book Value (P/TBV) multiple at roughly 0.60x to 0.65x. The Price-to-Earnings (P/E) ratio sits at an undemanding 6.5x to 8.8x trailing earnings.71 The dividend yield alone exceeds 8%, heavily supported by the 60% payout policy.
When compared to global peers, the discount is stark. U.S. large-cap banks like JPMorgan Chase and Bank of America routinely trade at 1.5x to 2.2x Tangible Book Value and mid-teens P/E multiples, reflecting their higher ROTEs (15-18%) and the safety of the U.S. regulatory and macroeconomic environment. Even within Europe, pure-play wealth managers or highly efficient Nordic banks trade at premiums to BNP.
Is the Discount Justified?
Historically, the discount was entirely justified. When BNP generated an 8% ROTE against an 11% Cost of Equity, it destroyed value, necessitating a price below book. However, at a sustained 11.6% ROTE, a fundamental disconnect has emerged between price and reality.
Applying a standard Gordon Growth Model framework to calculate the implied cost of equity:
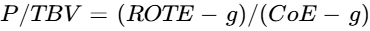
Assuming BNP can sustain its 2025 ROTE of 11.6%, and assuming a perpetual terminal growth rate () of 2% (in line with long-term European GDP and inflation targets):
0.65 = (0.116 – 0.02) / (CoE – 0.02)
0.65 * CoE – 0.013 = 0.096
0.65 * CoE = 0.109
CoE = 16.7%
The market is assigning an incredibly punitive ~16.7% implied cost of equity to BNP Paribas. This reflects deep, institutional skepticism regarding the durability of European banking returns and the belief that the current 11.6% ROTE will violently revert to the mean.
Catalysts for Re-rating:
For BNP to re-rate meaningfully higher (e.g., toward 0.85x – 0.90x TBV), three things must occur:
- Sustained ROTE Delivery Through the Easing Cycle: Management must unequivocally prove that an 11%+ ROTE is structural, not cyclical. If BNP can defend its margins through the 2026 ECB rate cuts by leaning on IPS fee growth (AXA IM) and CIB market share gains, market trust will build. Achieving the 2028 >13% ROTE target would mathematically force a re-rating.
- Relentless Capital Return: Management must aggressively and unapologetically execute buybacks at this 0.6x TBV level. Retiring 2-3% of the share float annually at a 40% discount to book value forces TBVPS to compound rapidly, generating value regardless of multiple expansion.
- Regulatory Stabilization: A pause in Basel capital inflation and tangible legislative progress on the EU Capital Markets Union would lower the perceived European regulatory risk premium.
VIII. SYNTHESIS
Analyzed strictly through the lens of competitive advantage, BNP Paribas is not an elite, monopolistic compounder in the vein of high-moat software or niche financial infrastructure companies. Operating a universal bank in the European Union inherently caps the ceiling on ultimate business quality. The regulatory constraints are draconian, the macroeconomic environment is sluggish, and capital is trapped by fragmented national borders that prevent true economies of scale in retail banking.
However, within the rigid confines of this difficult environment, BNP Paribas is undoubtedly a very good business. It is arguably the best-managed large-cap universal bank in Europe. It possesses a genuine, defensible moat built on corporate banking scale, technological investment, and product diversification, which successfully shields its earnings from the volatility of single-market economic shocks.
The financial performance validates this assessment. A bank that generates €12.2 billion in net income, maintains a pristine 1.6% NPL ratio through twin inflation and rate shocks, achieves an 11.6% return on tangible equity, and executes highly accretive capital reallocation—selling sub-scale U.S. retail assets at a premium to buy high-margin asset management capabilities and repurchase its own discounted stock—is not a value trap. Management’s capital allocation under Jean-Laurent Bonnafé has been disciplined, logical, and increasingly aligned with per-share value creation rather than empire-building.
The investment thesis rests entirely on a severe pricing dislocation. The market is currently pricing BNP Paribas with a nearly 17% implied cost of equity, acting as if the bank is destined to revert to the value-destroying, sub-8% ROTE days of the 2010s. If management simply executes on its base-case 2026-2028 trajectory—defending a >11% ROTE, integrating AXA IM successfully, and returning 60% of earnings via >8% dividend yields and accretive buybacks—the mechanical compounding of tangible book value will drive substantial shareholder returns, even without a multiple re-rating.
For an investor, the critical variables to monitor are whether the European Central Bank’s rate cutting cycle destroys the commercial bank’s net interest margin faster than the CIB and Asset Management divisions can grow fee income, and whether management maintains the discipline to buy back stock heavily while it remains this cheap.
Frequently Asked Questions
General Questions
- What thoughtful questions have other investors asked about this company? During the Q4 2025 earnings call, analysts (from firms like J.P. Morgan, Goldman Sachs, and Morgan Stanley) probed management heavily on the regulatory impacts of the Fundamental Review of the Trading Book (FRTB) on future capital requirements. They also questioned the strategic rationale behind the pending Athlon (car fleet leasing) acquisition, the mechanics of the newly announced structural transformation plan to cut support function costs, and the bank’s exact strategy for distributing excess capital above its 13% CET1 target.
Cyclicality & Earnings Nature
- Are earnings at a cyclical high or cyclical low? They appear to be at a cyclical high, though management is fighting to make this baseline structural. The bank posted record Q4 2025 net profit (up 28% year-over-year) and achieved an 11.6% Return on Tangible Equity (ROTE) for the full year.
- Are earnings driven primarily by the external environment or internal company actions? It is a mix. The recent earnings surge was heavily subsidized by the external environment—specifically high ECB interest rates and a massive surge in market volatility that drove equities and FICC (Fixed Income, Currencies, and Commodities) trading revenues to multi-year highs. However, internal actions are playing a massive role: the bank achieved €800 million in operating efficiency savings in 2025 alone and executed highly accretive M&A, like the AXA Investment Managers (AXA IM) integration.
- How stable are revenues? Revenues are highly stable due to the bank’s diversified universal model. While Corporate & Institutional Banking (CIB) trading revenues can fluctuate, the bank relies on massive, recurring fee streams from its Investment & Protection Services (IPS) division (which saw revenues jump 39.6% in Q4 2025) and sticky net interest income from its commercial banking networks.
- Outlook for the company’s products and services? The outlook is strong, particularly for capital-light, fee-generating services. The integration of AXA IM makes BNP the third-largest European asset manager. Management is targeting a >5% revenue compound annual growth rate (CAGR) from 2024-2026.
- How big will this market be? Is it growing? Shrinking? Domestic or international? The core European banking market is mature and generally slow-growing due to aging demographics and sluggish EU economic growth. However, BNP is offsetting domestic stagnation by capturing international market share in global banking (especially in the Americas) and expanding aggressively in pan-European wealth and asset management.
Business Quality & Competitive Moat
- Is the industry getting more or less competitive? It is becoming more competitive in the commoditized retail space due to digital challengers and fintechs, but less competitive (more consolidated) at the top tier of global investment banking and asset management, where immense scale is required to survive regulatory and technology costs.
- How profitable is this business? What is the return on capital invested? Return on equity? The bank is highly profitable today. In 2025, net income reached €12.2 billion with a ROTE of 11.6%. For specific capital deployments, the returns are very attractive: the AXA IM acquisition targets an 18% Return on Invested Capital (ROIC) by 2028, and the Arval/Athlon mobility integration targets an 18% ROIC by 2028.
- How profitable is this industry? Are there a lot of competitors? What are the barriers to entry? European banking has historically suffered from low profitability (averaging ~4.6% ROE compared to ~9.8% in the US) due to overcapacity and strict capital rules. Barriers to entry are immense: the top 12 global banks spend a combined $34 billion annually just on technology, and regulatory hurdles like Basel IV mechanically inflate capital requirements.
- Can this business be easily understood? No. As a globally systemically important bank (G-SIB) operating in 64 countries with a €2.8 trillion balance sheet spanning complex derivatives, retail lending, and asset management, its internal mechanics and risk weightings are highly opaque.
- Can this company be undermined by foreign, low-cost labor? Not directly, as banking requires local regulatory licensing and relationship networks. However, agile, cloud-native fintechs can undermine specific high-margin businesses like cross-border payments.
- Do brands matter? Yes. In wealth management, corporate advisory, and global markets, the BNP Paribas brand signals balance sheet safety, counterparty reliability, and execution certainty during market panic.
- What are the customer switching costs? Very high in corporate banking. Untangling global cash management, trade finance facilities, and customized derivative hedges from a primary bank is incredibly costly and risky for a corporate treasurer.
Financial Condition & Balance Sheet
- Does the company have assets that are not fully recognized in the balance sheet? Yes, off-balance sheet customer assets (Assets under Management). Following the AXA IM acquisition, total AUM surpassed €1.6 trillion, generating massive fee income without requiring equivalent regulatory capital.
- What off-balance sheet liabilities does the company have? The bank holds significant off-balance sheet financing commitments and guarantee commitments given to corporate clients. As of 2025, total off-balance sheet impaired commitments (stage 3) stood at approximately €2.1 billion.
- How conservative is the company’s accounting? Highly conservative. Governed by the ECB and IFRS 9 standards, BNP provisions aggressively for expected credit losses. As of Q4 2025, the Non-Performing Loan (NPL) ratio was a pristine 1.6% with a high stage 3 coverage ratio of 66.9%.
- How CapEx hungry is this business? Massively. To drive down its cost-to-income ratio, BNP is deploying AI at scale (targeting 1,000 live use cases by 2025) and undergoing a complete structural transformation of its IT and support functions.
Capital Allocation & Management
- How much free cash flow does the business generate? How does management use this free cash flow? In banking, “free cash flow” is organic capital generation, which runs at roughly 30 basis points of CET1 per quarter. Management’s philosophy is highly shareholder-friendly: they maintain a 60% payout ratio (minimum 50% in cash dividends, 10% in buybacks). Crucially, starting in 2027, the bank will calculate any excess capital above its 13% CET1 target at year-end and redistribute it entirely to shareholders.
- Has the company made any significant acquisitions recently? Yes. In July 2025, it closed the €5.1 billion acquisition of AXA IM. In October 2025, it acquired HSBC’s private banking activities in Germany, and it is integrating Athlon into its Arval fleet leasing business.
- Is the company buying back shares? Yes. The bank finalized a €1.15 billion share buyback program in December 2025.
- Does the company issue large amounts of new shares to insiders? No. The share count is actively shrinking due to buybacks.
- What is the compensation policy of directors and management? Compensation is strictly regulated under European CRD5 rules, linking pay to multi-year risk management, financial performance, and ESG metrics. CEO Jean-Laurent Bonnafé’s total compensation was approximately €4.3 million in 2024, which is relatively conservative compared to US banking peers.
- What are the motivations of management? Management is heavily motivated to hit the newly raised 2028 targets: pushing ROTE above 13%, cutting the cost-to-income ratio below 56%, and generating >10% Net Income CAGR.
Valuation & Market Data
- Is the stock an ADR? MLP? K-1? The primary listing is on Euronext Paris (BNP.PA). US investors can trade it via an American Depositary Receipt (ADR) under the ticker BNPQY. It is a standard C-Corp equivalent, so it does not issue a K-1.
- Dividend Policy? The bank pays out 50% of earnings in cash. The total dividend for 2025 is €5.16 per share (up 7.7% YoY), and the bank recently transitioned to a semi-annual payment schedule to smooth investor cash flows.
- Is net income diverging from cash from operations? Operating cash flows in banking fluctuate wildly year-to-year based on customer deposit inflows and loan originations. However, the underlying net income (€12.2 billion) is of high quality and perfectly tracks pre-tax income (€17.06 billion) without major accounting distortions.
Risks & Downside
- What factors would cause the stock to decline? A severe European recession leading to corporate bankruptcies would spike the cost of risk (currently benign at 34 bps). Furthermore, if ECB rate cuts compress the net interest margin faster than fee income can grow, or if the impending Basel IV FRTB rules inflate Risk-Weighted Assets drastically, capital returns could be suspended.
- What is the risk of a catastrophic loss / chance of a total loss? Exceedingly low. The bank’s CET1 ratio is 12.6% (against a 10.42% minimum requirement), and its loan book is radically diversified, with no single corporate sector making up more than 4% of total group exposures.
Recent News & Events
- Has the business environment changed recently? Yes, the macroeconomic environment is shifting from high inflation/rate hikes to ECB rate cuts. Simultaneously, global trade faces renewed fragmentation and US tariff risks under the new administration, which could disrupt cross-border corporate banking flows.
- Has the company recently changed accounting policies? In late 2025, to align with market practices, BNP began including conversion and revaluation reserves in its tangible equity calculation, which had a +0.3% mechanical boost to its baseline ROTE.
- Recent changes in management? While Jean-Laurent Bonnafé remains CEO, shareholders overwhelmingly voted in May 2025 to raise the mandatory retirement age for the CEO, allowing the 63-year-old executive to potentially remain in power until the 2031 annual meeting. This secures stability but highlights a lack of an immediate, obvious successor.
Works cited
- Bank of America Investment Analysis, https://drive.google.com/open?id=1hAsecYWJpZ4DsssJSPIbzwdJOzQYlKYSvVcg0UWoCbY
- What is Competitive Landscape of Credit Agricole Company?, accessed February 28, 2026, https://swottemplate.com/blogs/competitors/credit-agricole-competitors
- Crédit Agricole Investment Analysis , https://drive.google.com/open?id=1muyVlXLT3FFyp9vmO1IhzdIlGX_PGeEUZWWl-i8W-Cg
- What is Competitive Landscape of BNP Paribas Company?, accessed February 28, 2026, https://pestel-analysis.com/blogs/competitors/bnpparibas
- Europe’s 50 largest banks by assets, 2025 | S&P Global, accessed February 28, 2026, https://www.spglobal.com/market-intelligence/en/news-insights/articles/2025/4/europes-50-largest-banks-by-assets-2025-88404022
- EU structural financial indicators: end of 2024, accessed February 28, 2026, https://www.ecb.europa.eu/press/pr/date/2025/html/ecb.pr250612_1~6afb2dc0f9.en.html
- FACTS AND FIGURES – EBF – European Banking Federation, accessed February 28, 2026, https://www.ebf.eu/factsandfigures/
- Bank profitability in the euro area in times of high inflation, accessed February 28, 2026, https://www.pse-journal.hr/en/archive/bank-profitability-in-the-euro-area-in-times-of-high-inflation_13444/
- Evidence from the Euro Area during the Crisis and Post-Crisis Period, accessed February 28, 2026, https://www.researchgate.net/publication/334380122_Determinants_of_Banks’_Net_Interest_Margin_Evidence_from_the_Euro_Area_during_the_Crisis_and_Post-Crisis_Period
- European banks: Outlook in 2025… and beyond – Funcas, accessed February 28, 2026, https://www.funcas.es/wp-content/uploads/2025/02/4.-European-banks.pdf
- Euro Area Interest Rate – Trading Economics, accessed February 28, 2026, https://tradingeconomics.com/euro-area/interest-rate
- BNP Paribas 2024 Integrated Report, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/BNP-Paribas-Integrated-Report-2024.pdf
- French banks’ profitability to lag behind European peers until late 2025, accessed February 28, 2026, https://www.leasinglife.com/news/french-banks-profitability-to-lag-behind-european-peers-until-late-2025-fitch/
- Acceleration & Resilience – BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/document/acceleration-resilience-rote-ambition-at-13-in-2028-cet1-ratio-at-12-5-by-end-2027
- The implementation of Basel III: progress, divergence and policy, accessed February 28, 2026, https://www.europarl.europa.eu/RegData/etudes/IDAN/2025/773694/ECTI_IDA(2025)773694_EN.pdf
- A recap of the Basel IV regulation and it’s timeline – MORS Software, accessed February 28, 2026, https://morssoftware.com/basel-iv-regulation-recap/
- Basel IV is here: What you need to know | Nordea, accessed February 28, 2026, https://www.nordea.com/en/news/basel-iv-is-here-what-you-need-to-know
- Basel IV / CRR III – KPMG International, accessed February 28, 2026, https://kpmg.com/de/en/insights/corporate-governance-and-compliance/basel-4.html
- Basel IV – A Jurisdictional Breakdown – Regnology, accessed February 28, 2026, https://www.regnology.net/en/resources/insights/basel-iv-a-jurisdictional-breakdown/
- AFME report identifies Banking Union challenges holding back EU, accessed February 28, 2026, https://www.afme.eu/news-insights/press-releases/afme-report-identifies-banking-union-challenges-holding-back-eu-bank-consolidation/
- European Banking M&A Surges In 2025 – Oliver Wyman, accessed February 28, 2026, https://www.oliverwyman.com/our-expertise/insights/2025/may/5-themes-driving-european-banking-mergers-acquisitions-2025.html
- The Political and Strategic Challenges to European Banking M&A, accessed February 28, 2026, https://www.bitget.com/news/detail/12560604939831
- Interview with Jean-Laurent Bonnafé – Page 9 | BNP Paribas – 2024, accessed February 28, 2026, https://integrated-report.bnpparibas/2024/article/9/
- The challenges we face collectively – Page 22 – 2024 integrated report, accessed February 28, 2026, https://integrated-report.bnpparibas/2024/article/22/
- corporate governance – BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/document/bnp-paribas-corporate-governance-april-2025
- BNP Paribas – Wikipedia, accessed February 28, 2026, https://en.wikipedia.org/wiki/BNP_Paribas
- FOURTH QUARTER AND FULL-YEAR 2025 RESULTS – BNP Paribas, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/PR_BNPP_4Q25_Results_EN.pdf
- BNP Paribas-4Q25-Results, accessed February 28, 2026, https://invest.bnpparibas/en/document/4q25-slides
- FIRST QUARTER 2025 RESULTS – BNP Paribas, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/PR_BNPP_1Q25_Results_EN.pdf
- The 12 top investment banks spent $34bn on technology in 2024, accessed February 28, 2026, https://www.efinancialcareers.com/news/the-12-top-investment-banks-spent-34bn-on-technology-in-2024
- COALITION GREENWICH STUDY CONFIRMS BNP PARIBAS’ TOP, accessed February 28, 2026, https://cashmanagement.bnpparibas.com/our-solutions/trends-vision/coalition-greenwich-study-confirms-bnp-paribas-top-position-large
- 2024 ANNUAL RESULTS – 27 February 2025 – La Banque Postale, accessed February 28, 2026, https://www.labanquepostale.com/content/dam/lbp/documents/communiques-de-presse/2025/LBP_FY2024_Results_EN.pdf
- French banks face further income squeeze as regulated savings rate, accessed February 28, 2026, https://www.spglobal.com/market-intelligence/en/news-insights/articles/2023/1/french-banks-face-further-income-squeeze-as-regulated-savings-rate-rises-again-73840687
- French bank quarterly: net interest margins to remain low for longer, accessed February 28, 2026, https://www.scoperatings.com/ScopeRatingsApi/api/downloadstudy?id=007de76e-f46e-4f90-915d-7c2fa2686b7d
- BNP Paribas’ €14.5 Bn Acquisition of Fortis Bank (BE, LU), accessed February 28, 2026, https://mnawatch.com/financial-retrospectives/d5wdvbhj0q9ygpgg4btkmjuwjmuvwb
- BNP Paribas completes the acquisition of Fortis Bank and forms a, accessed February 28, 2026, https://group.bnpparibas/en/press-release/bnp-paribas-completes-acquisition-fortis-bank-forms-strategic-partnership-insurance-fortis
- Annual Report 2024 – BNP Paribas Fortis, accessed February 28, 2026, https://www.bnpparibasfortis.com/docs/default-source/key-documents-(en—fr—nl)/en/annual_report_2024_bnp_paribas_fortis_en.pdf
- The Italian NPE Market | The times they are a-changin’ – PwC, accessed February 28, 2026, https://www.pwc.com/it/it/publications/npl/doc/the-italian-NPE-market-dec2024.pdf
- consolidated results as at 30 september 2025 – Intesa Sanpaolo, accessed February 28, 2026, https://group.intesasanpaolo.com/en/investor-relations/press-releases/2025/10/20251031-ris3q25-uk
- The Italian NPE Market | The Great Beyond – PwC, accessed February 28, 2026, https://www.pwc.com/it/it/publications/npl/doc/PwC_NPE-ottobre25.pdf
- third quarter 2025 results – BNP Paribas, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/PR_BNPP_3Q25_Results_EN.pdf
- Breaking Down BNP Paribas SA Financial Health – DCFmodeling.com, accessed February 28, 2026, https://www.dcfmodeling.com/blogs/health/bnppa-financial-health
- A growth trajectory fueled by a powerful business model – BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/document/conferences-roadshows-september-2023
- URD 2024 – EN – BNP Paribas, accessed February 28, 2026, https://reports.invest.bnpparibas/esef/2024/bnpp-2024-12-31-en.html
- Sell-side global markets trading revenue analysis 2024, accessed February 28, 2026, https://coalitiongreenwich.crisil.com/content/dam/coalition-greenwich/Reports/2025/25-2022-sell-side-global-markets-trading-revenue-analysis-2024/Sell-side-global-markets-trading-revenue-analysis-2024-25-2022.pdf
- GlobalCapital Derivatives Awards 2025 – BNP Paribas Global Markets, accessed February 28, 2026, https://globalmarkets.cib.bnpparibas/globalcapital-derivatives-awards-2025/
- Equities trading boom to fuel 10% rise in 2025 investment bank, accessed February 28, 2026, https://www.spglobal.com/market-intelligence/en/news-insights/articles/2025/12/equities-trading-boom-to-fuel-10-rise-in-2025-investment-bank-revenues-95709884
- Geopolitics, political uncertainty, operating … – Scope ratings, accessed February 28, 2026, https://www.scoperatings.com/ratings-and-research/research/EN/179859
- FOURTH QUARTER AND FULL-YEAR 2024 RESULTS, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/PR_BNPP_4Q_Annual_Results_2024_EN.pdf
- Results and publications | Investors & Shareholders – BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/en/results
- BNP Paribas SA Pre-Tax Income 2012-2025 | BNPQY – Macrotrends, accessed February 28, 2026, https://www.macrotrends.net/stocks/charts/BNPQY/bnp-paribas-sa/pre-tax-income
- BNP Paribas SA Revenue 2012-2025 | BNPQY – Macrotrends, accessed February 28, 2026, https://www.macrotrends.net/stocks/charts/BNPQY/bnp-paribas-sa/revenue
- BNP Paribas SA EPS – Earnings per Share 2012-2025 | BNPQY, accessed February 28, 2026, https://www.macrotrends.net/stocks/charts/BNPQY/bnp-paribas-sa/eps-earnings-per-share-diluted
- 1ST QUARTER 2025 – BNP Paribas, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/Slides_BNPP_1Q_2025_Results_EN.pdf
- BNP Paribas First Quarter 2025 Results, accessed February 28, 2026, https://invest.bnpparibas/document/first-quarter-2025-results-transcript
- BNP Paribas : CET1 ratio target raised to 13% by 2027 and ECB, accessed February 28, 2026, https://group.bnpparibas/en/press-release/bnp-paribas-cet1-ratio-target-raised-to-13-by-2027-and-ecb-authorisation-for-eur1-15-billion-share-buyback-program
- What is Growth Strategy and Future Prospects of BNP Paribas, accessed February 28, 2026, https://portersfiveforce.com/blogs/growth-strategy/bnpparibas
- 3 minutes to (re)discover BNP Paribas’ 2025 highlights! – BNP Paribas, accessed February 28, 2026, https://group.bnpparibas/en/news/3-minutes-to-re-discover-bnp-paribas-2025-highlights
- Debt Investors Presentation – 3Q25 | BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/en/document/debt-investors-presentation-3q25
- BNP Paribas Cardif, record activity in 2024, driven by strong savings, accessed February 28, 2026, https://www.bnpparibascardif.com/en/bnp-paribas-cardif-record-activity-in-2024-driven-by-strong-savings-momentum-and-robust-partnerships/
- Jean-Laurent Bonnafé – Wikipedia, accessed February 28, 2026, https://en.wikipedia.org/wiki/Jean-Laurent_Bonnaf%C3%A9
- BNP Paribas shareholders approve higher age limit for CEO, accessed February 28, 2026, https://www.bankingdive.com/news/bnp-paribas-shareholders-raise-ceo-age-limit-bonnafe-succession/747981/
- 2024 Full Year Results – Groupe BNP Paribas, accessed February 28, 2026, https://cdn-group.bnpparibas.com/uploads/file/Slides_BNPP_4Q_2024_Businesses_Appendices_EN.pdf
- FOURTH QUARTER AND 2024 FULL YEAR – BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/document/4q24-slides
- Investment analysis of BNP Paribas – Freedom24, accessed February 28, 2026, https://freedom24.com/ideas/details/17745
- Fourth Quarter and Full Year 2025 Results – BNP Paribas, accessed February 28, 2026, https://invest.bnpparibas/document/resultats-au-31-decembre-2025-transcript
- EUROPEAN PROPERTY MARKET – BNP Paribas Real Estate, accessed February 28, 2026, https://www.realestate.bnpparibas.com/sites/default/files/2025-02/2025-01-20%20FR%20Forecast_H12025_Feb26.pdf
- 2026 US M&A outlook: key themes defining dealmaking, accessed February 28, 2026, https://cib.bnpparibas/2026-us-ma-outlook-key-themes-defining-dealmaking/
- The challenges we face collectively – Page 20 – 2024 integrated report, accessed February 28, 2026, https://integrated-report.bnpparibas/2024/article/20/
- Compliance: find out more about our policy | BNP Paribas Group, accessed February 28, 2026, https://group.bnpparibas/en/group/our-governance/compliance
- BNPQY (BNP Paribas) PE Ratio (TTM) – GuruFocus, accessed February 28, 2026, https://www.gurufocus.com/term/pettm/BNPQY
- P/E Ratio For BNP Paribas SA (BNP) – Finbox, accessed February 28, 2026, https://finbox.com/XTRA:BNP/explorer/pe_ltm/