
Executive Summary
ZIM Integrated Shipping Services Ltd. (NYSE: ZIM) represents a highly complex, atypical profile within the global equities market. Analyzed strictly through the fundamental framework of durable competitive advantage and long-term capital compounding, the container shipping industry is structurally deficient. It is a notoriously capital-intensive, highly cyclical, and fiercely commoditized sector characterized by chronic overcapacity, zero product differentiation, and immense operating leverage. Within this environment, ZIM possesses no sustainable structural moat. The company acts as a pure price-taker, heavily exposed to the extreme volatility of the spot freight market, operating an “asset-light” charter model that shifts traditional capital expenditure into massive, fixed operating lease liabilities. This model mathematically amplifies both the peaks of industry upcycles and the severe margin destruction of cyclical troughs.
However, any purely fundamental evaluation of ZIM’s long-term terminal value was entirely superseded on February 16, 2026. German shipping behemoth Hapag-Lloyd announced a definitive agreement to acquire 100% of ZIM’s outstanding shares for $35.00 per share in an all-cash transaction, valuing the equity at approximately $4.2 billion.1 This buyout offer represents a staggering 126% premium over the company’s unaffected share price of $15.50 in August 2025, prior to the emergence of takeover speculation.2
Because ZIM is considered a strategic national asset by the State of Israel, the transaction involves a highly intricate structural carve-out to satisfy the government’s “Golden Share” veto power. Israel’s FIMI Opportunity Funds will acquire a subset of the business—16 owned vessels, domestic routes, and the ZIM brand—to form an independent entity dubbed “New ZIM”.1 Concurrently, Hapag-Lloyd will absorb ZIM’s highly lucrative international routes and its 99 chartered vessels, elevating Hapag-Lloyd to a dominant top-four position on the critical Transpacific trade lane.2
This report exhaustively deconstructs ZIM’s historical business model, its aggressive capital allocation framework, the macroeconomic forces dictating the current shipping capital cycle, and the critical merger arbitrage dynamics currently defining its equity pricing. The central thesis is that while ZIM is a fundamentally poor business operating in a structurally hostile industry, its management team has executed a masterful cycle-timing strategy. By extracting massive dividend yields during the exogenous boom years of 2021-2022 and 2024, and subsequently securing an acquisition exit at a massive premium just as the industry faces a historic capacity glut in 2026, management has successfully bridged the gap between a low-quality business model and elite shareholder value creation.
I. Industry Dynamics & Macroeconomic Environment (2023–2026)
To contextualize ZIM’s financial trajectory, one must comprehensively understand the macroeconomic whiplash that has defined the container shipping sector over the past half-decade. The industry is fundamentally governed by severe boom-and-bust capital cycles. Extended periods of high freight rates inevitably trigger massive vessel orderbooks at global shipyards, which, upon delivery, result in structural overcapacity, rate collapses, and prolonged periods of capital destruction.
The Post-COVID Normalization and the Red Sea Exogenous Shock
Following the unprecedented, multi-billion-dollar profitability of the 2020-2022 COVID-19 supply chain crisis—a period defined by extreme port congestion and consumer goods demand—container shipping rates normalized rapidly. Throughout 2023, the industry experienced a severe reversion to the mean. By the end of 2023, ZIM reported an adjusted EBIT loss of $422 million and a net loss of $2.69 billion (heavily impacted by a $2.06 billion non-cash impairment charge on its assets), signaling the beginning of what was expected to be a prolonged structural downcycle.6
However, the industry’s supply-demand dynamics were violently inverted by a sudden, exogenous geopolitical shock in late 2023 and 2024: the outbreak of Iran-backed Houthi rebel attacks on commercial vessels in the Red Sea and the Bab-el-Mandeb strait.8 The Red Sea is the primary maritime gateway connecting Asia to Europe and the Mediterranean via the Suez Canal, historically handling 25% to 30% of total global container shipping volumes.8 The targeted attacks effectively closed this vital corridor to major Western and Israeli-linked carriers.
In response, major shipping lines, including ZIM, were forced to radically alter their global networks, diverting vessels southward around the Cape of Good Hope in Africa. This massive logistical diversion added approximately 7,000 to 11,000 nautical miles to standard Asia-Europe journeys, extending transit times by 10 to 15 days, and in some cases, up to 25 days.9 The macroeconomic mechanism of this diversion was profound: by drastically increasing the distance of each voyage, the industry required significantly more vessels to maintain standard weekly service schedules. This artificial elongation of the supply chain instantly absorbed the industry’s looming excess capacity, effectively removing an estimated 7% to 11% of effective global vessel supply from the market.11
This geopolitical dislocation tightened supply and triggered a massive, immediate spike in spot freight rates. For the full year 2024, ZIM capitalized heavily on this dynamic. The company’s average freight rate per TEU (Twenty-foot Equivalent Unit) surged 57% year-over-year to $1,888.6 Driven by this pricing power and front-loaded consumer demand, ZIM carried a record 3.75 million TEUs in 2024, generating $8.43 billion in total revenue and an astonishing $2.15 billion in net income.6 The Red Sea crisis essentially granted the industry a highly lucrative, multi-quarter reprieve from its structural overcapacity issues.
The 2025 Margin Compression and Rate Normalization
The pricing power afforded by the Red Sea crisis, while lucrative, proved entirely transient. The financial data from 2025 demonstrates clear, aggressive signs of rate normalization and margin compression across the sector.
By the third quarter of 2025, the market reality began to reflect the underlying supply fundamentals. ZIM’s Q3 2025 average freight rate fell 35% year-over-year to $1,602 per TEU.14 Consequently, Q3 2025 revenue contracted by 36% year-over-year to $1.78 billion, and net income collapsed by 89% to $123 million (down from $1.13 billion in Q3 2024).14 The company’s Adjusted EBIT margin contracted violently from 45% in Q3 2024 to just 15% in Q3 2025.14
This deterioration was not isolated to ZIM; it was a systemic industry phenomenon. In Q3 2025, Hapag-Lloyd reported an 85% decline in net profit, HMM’s profit plunged 83%, and Maersk’s ocean shipping segment saw its average revenue per TEU drop by approximately 31%.11 Despite solid volume growth driven by robust global trade and shippers front-loading cargo to avoid anticipated US tariff hikes, the sheer influx of new vessel deliveries decoupled volume gains from yield improvement.11 The data confirms an absolute lack of structural pricing power; the container shipping market remains entirely dictated by exogenous supply-demand imbalances. When the artificial constraints of the Red Sea diversions became priced into the network and normalized, carriers immediately lost their ability to sustain premium rates.
The 2026 Outlook: A Severe Structural Downcycle
The macroeconomic and supply-side outlook for 2026 indicates a highly unfavorable, hostile environment for ocean carriers. The industry is currently facing a vessel orderbook of historic, unprecedented proportions. According to maritime analytics firms and industry reports, approximately 11.5 million TEU in newbuild capacity is scheduled for delivery between 2026 and 2029.11 This impending influx represents roughly 35% of the currently active global fleet, an overwhelming wave of steel that threatens to drown out any marginal gains in global trade demand.11
While global container shipping demand is forecast to grow by a modest 2% to 3% in 2026—closely mirroring global GDP growth with a trade-to-GDP multiplier reverting to 1.0x—fleet supply is expected to expand by at least 3.6% in 2026 alone, compounding the existing overcapacity.17 Furthermore, the industry faces the latent threat of a Red Sea resolution. Should geopolitical tensions ease and the Suez Canal fully reopen to commercial traffic, the return of diverted vessels to shorter traditional routes would inject an estimated 11% of “hidden” capacity back into the active market simultaneously.11
The pricing implications of this supply glut are severe. Xeneta’s 2026 Ocean Outlook projects that global average spot rates could fall by 25% for the full year 2026, and long-term contract rates could decline by 10%, pushing the sector’s profitability back to, or below, pre-pandemic levels.17 In the absence of massive industry consolidation, aggressive capacity management, or coordinated vessel scrapping (which remains at twenty-year lows), the sector is fundamentally entering a profound, structural downcycle.11
II. Competitive Position & Business Model Architecture
ZIM operates as a mid-tier global carrier, holding an approximate 2.3% to 2.4% global market share.19 With an operating capacity of roughly 713,000 to 767,000 TEU across 115 to 130 vessels, ZIM ranks as the 9th or 10th largest container shipping company globally.5 To survive and compete against industry behemoths like Mediterranean Shipping Company (MSC, with a 20%+ share and over 6.6 million TEU) and A.P. Moller-Maersk (14%+ share and over 4.6 million TEU), ZIM utilizes a distinct, highly leveraged operational framework.20
The “Asset-Light” Charter Strategy
The defining structural characteristic of ZIM’s business model is its extreme reliance on chartered tonnage, deliberately eschewing the traditional model of heavy vessel ownership. As of late 2025, of ZIM’s roughly 115 to 128 operated containerships, approximately 99 to 113 are chartered from external shipowners, with only 15 to 16 vessels fully owned by the company.4 Furthermore, all 14 to 15 of its specialized car carrier vessels are chartered.7 Consequently, roughly 87% or more of ZIM’s total operated capacity is leased rather than owned.23
Management consistently markets this as an “asset-light” or “agile” strategy, but from a rigorous financial perspective, this nomenclature is highly misleading. While ZIM avoids the massive initial capital expenditures (Capex) required to commission newbuilds from shipyards, it capitalizes these long-term vessel leases on its balance sheet as right-of-use liabilities under IFRS 16 accounting standards. As of December 31, 2024, ZIM carried a staggering $5.92 billion in lease liabilities at a weighted average interest rate of 8.1%.24
The Upcycle Advantage: In periods of soaring demand and high freight rates, the charter model provides distinct advantages. It allows ZIM to rapidly scale its capacity to capture spot market premiums without enduring the two-to-three-year lead times required for shipyard construction. This extreme operating leverage allows revenue to flow directly to the bottom line during capacity crunches, generating exponential returns on equity. The Downcycle Disadvantage: During a rate collapse, the charter model transforms into a severe liability. ZIM is locked into fixed daily charter-hire payments for vessels on multi-year contracts, regardless of whether those ships are sailing at 100% utilization or completely empty. Unlike Maersk or Hapag-Lloyd, which own a much larger percentage of their fleets (Hapag-Lloyd’s charter ratio is roughly 39% to 51%) and can physically idle ships or scrap older tonnage to lower their carrying costs during recessions, ZIM must continue servicing its massive lease obligations.1 The “asset-light” model does not eliminate risk; it simply shifts capital risk into operating leverage risk, ensuring maximum margin destruction during industry troughs.
Trade Lane Focus and Spot Market Exposure
ZIM focuses predominantly on the Transpacific (Asia to US West Coast and East Coast), Intra-Asia, and Latin America trade lanes.19 Crucially, ZIM has historically maintained a much higher exposure to the spot freight market than its larger peers. While legacy carriers often lock in 50% to 70% of their annual volume on long-term fixed-rate contracts with major retailers, ZIM’s spot exposure can reach up to 70% of its volume on specific routes.26
This strategic choice makes ZIM a high-beta proxy for global freight indices like the Shanghai Containerized Freight Index (SCFI). During the 2021-2022 and 2024 supply chain crises, this unhedged spot exposure generated unprecedented windfall profits, allowing ZIM to capture peak pricing while peers were locked into lower legacy contracts. However, as explicitly noted in the Q3 2025 financial results, this extreme leverage works aggressively against the carrier during rate normalizations. When spot rates plummet, ZIM’s revenues collapse immediately, offering no contractual buffer to protect margins.11
Fleet Modernization and LNG Investment
Recognizing the structural cost disadvantage of operating older, fuel-inefficient chartered vessels, ZIM’s management executed a massive, multi-year fleet renewal program between 2021 and 2025. The company secured delivery of 46 modern newbuild vessels, primarily through long-term charter agreements with major tonnage providers like Seaspan and Navios.26
The critical differentiator of this renewal program is fuel propulsion: 28 of these 46 newbuilds are dual-fuel vessels capable of operating on Liquefied Natural Gas (LNG).26 By the end of 2025, approximately 40% of ZIM’s operated capacity is LNG-powered.22 This modernization provides ZIM with one of the most carbon-efficient fleets in the mid-tier segment. Operationally, it lowers unit costs by reducing reliance on highly volatile, traditional low-sulfur fuel oil (VLSFO) bunker costs, and strategically, it positions the company to mitigate the financial impact of incoming regulatory carbon taxes, such as the European Union’s Emissions Trading System (EU ETS) and the IMO’s Net-Zero Framework mandates.11
Scale, Network, and the Illusion of Differentiation
In the commoditized business of container shipping, scale is the absolute primary driver of unit economics. The “Big Five” carriers utilize their massive volume to dictate terms at major ports, negotiate superior terminal handling charges, and operate highly efficient hub-and-spoke networks that minimize empty container repositioning costs.
ZIM’s sub-3% market share leaves it operating at a permanent structural disadvantage as a price-taker. Container shipping offers virtually zero product differentiation; a twenty-foot box moved by ZIM from Shanghai to Los Angeles is functionally indistinguishable to a shipper from one moved by Evergreen or ONE. To compensate for its lack of organic scale, ZIM relies heavily on Vessel Sharing Agreements (VSAs) and operational cooperation, most notably its partnership with MSC on key Asia-US East Coast routes.25 While this cooperation allows ZIM to offer a broader service network than it could independently, it does not confer a proprietary competitive advantage, as the underlying economics remain tethered to the efficiency of the larger partner.
III. Evidence of Competitive Advantage (Or Lack Thereof)
A core, foundational tenet of rigorous fundamental investment analysis dictates that a company only possesses a durable competitive advantage (a “moat”) if it can consistently generate a Return on Invested Capital (ROIC) superior to its Weighted Average Cost of Capital (WACC) across a full, multi-year business cycle. If a business only exceeds its cost of capital during rare, exogenous macroeconomic spikes, it is a commodity business riding a cycle, not a compounder of value.
Financial Performance Metrics Over a Full Cycle
An analysis of ZIM’s return metrics over the past six years demonstrates extreme, violent volatility. This data signature is indicative of a price-taking business driven entirely by macro pricing rather than proprietary value creation or structural superiority.
| Financial Metric | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | Q3 2025 (TTM) |
| Operating Margin | -0.04% | 13.55% | 52.75% | 47.98% | -54.54% | 30.0% | 15.0% |
| Net Margin | Negative | 13.1% | 43.3% | 36.8% | -52.0% | 26.0% | 13.2% |
| Return on Equity (ROE) | Negative | ~73.3% | 191.0% | ~131.6% | Negative | 25.3% | 25.18% |
| ROIC | Negative | 53.2% | 160.5% | 107.7% | -28.0% | 27.3% | 12.7% |
(Data compiled and aggregated from official filings and financial data sources 6)
The Boom Anomaly (2021-2022 & 2024): During the peak of the COVID-19 supply chain crisis, ZIM’s ROIC reached an absurd, economically unsustainable 160.5%.30 Because of its asset-light model and heavy spot market leverage, ZIM’s operating margins eclipsed 52%, allowing it to capture disproportionate upside during the capacity crunch.31 A similar, though muted, dynamic occurred in 2024 during the Red Sea crisis, pushing ROIC back up to 27.3%.28
The Bust Reality (2023 & Late 2025): The true nature of the business is revealed when freight rates normalize. In 2023, as rates collapsed, ZIM’s operating margin plunged to a devastating -54.5% (exacerbated by a $2.06 billion non-cash impairment charge on its assets), and ROIC fell to a highly destructive negative 28.0%.28 As of Q3 2025, the trailing twelve-month ROIC has compressed back down to 12.7% as rates continue to fall.28
WACC Comparison: ZIM’s estimated Weighted Average Cost of Capital (WACC) generally fluctuates between 7.0% and 9.8% depending on the exact beta and risk-free rate assumptions utilized.28 While the Q3 2025 TTM ROIC of 12.7% technically clears the hurdle rate, forward estimates for 2026—factoring in the 25% projected drop in spot rates—suggest a rapid, inevitable return to sub-WACC profitability and value destruction.
The Verdict on the Moat: “Commodity Hell”
Evaluated against the framework of competitive advantage, ZIM possesses no structural moat whatsoever.
- No Pricing Power: ZIM provides a strictly commoditized service. It cannot charge a premium over market indices for moving a container.
- No Cost Leadership: While the new LNG fleet improves specific unit costs, ZIM completely lacks the sheer megamax-vessel scale of MSC or the integrated logistics infrastructure of Maersk to command the lowest absolute cost-per-TEU in the industry.
- No Switching Costs: Freight forwarders and Beneficial Cargo Owners (BCOs) face zero friction in switching carriers. Decisions are made almost entirely based on weekly spot rate indices and basic schedule reliability.
- No Network Effects: The value of ZIM’s service does not increase non-linearly with each additional customer added to a vessel.
ZIM is a classic high-beta cyclical entity. It is a fundamentally “bad business” operating in a “commodity hell” that relies entirely on exogenous geopolitical shocks and supply chain failures to print cash.
IV. Growth History & Future Constraints
Analyzing growth in the container shipping industry requires divorcing organic business execution from macroeconomic rate inflation.
Revenue and Capacity Growth (2019-2025)
ZIM’s top-line revenue exhibits massive nominal growth, scaling from roughly $3.3 billion in 2019 to $8.43 billion in 2024.6 However, an attribution analysis reveals that this “growth” was almost entirely driven by rate inflation rather than structural market share capture.
For the full year 2024, ZIM achieved a record carried volume of 3.75 million TEUs, representing a 14% year-over-year volumetric growth.6 However, this volumetric growth was dwarfed by a 57% surge in the average freight rate to $1,888 per TEU.6 By 2025, the illusion of growth vanished alongside the rates. In the first nine months of 2025, ZIM’s carried volume was functionally flat year-over-year (2.765 million TEUs vs 2.768 million TEUs in 2024, a 0.1% decrease).14 Concurrently, the average freight rate dropped 14.1% to $1,622, resulting in a 13% contraction in total revenue to $5.42 billion.35
Future Growth Prospects and Constraints
True, organic, high-margin growth is functionally impossible for ZIM as a standalone entity in the current environment.
- Macro Constraints: Global container volume growth is tightly tethered to global GDP. With the WTO and IMF projecting sluggish trade-to-GDP multipliers, baseline industry volume growth is capped in the low single digits.17
- Competitive Constraints: The industry is heavily consolidated into massive alliances. The newly formed “Gemini Cooperation” (Maersk and Hapag-Lloyd) and the extended “Ocean Alliance” (CMA CGM, COSCO, Evergreen) control the vast majority of East-West trade lanes.36 ZIM, operating largely outside these core alliances, lacks the capital to engage in a predatory price war to seize market share against state-backed entities like COSCO or integrated giants like MSC.
- Capital Constraints: The “asset-light” model inherently limits equity-driven capacity expansion. To grow its fleet, ZIM must convince external shipowners (tonnage providers) to finance and build new ships on its behalf, locking ZIM into rigid long-term lease liabilities.
In a commoditized market facing a 35% supply influx, pursuing aggressive volume growth is a recipe for margin suicide.
V. Capital Allocation & Shareholder Returns
If a business lacks a structural moat but occasionally prints massive free cash flow due to cyclical peaks, the ultimate determinant of long-term shareholder value is management’s capital allocation. In this specific arena, CEO Eli Glickman and the ZIM board of directors have demonstrated exceptional, pragmatic discipline.
The Dividend Policy: Aggressive Capital Extraction
In highly cyclical, capital-intensive industries, management teams routinely destroy shareholder value through “empire building”—using peak-cycle earnings to acquire expensive competitors or order new fleets at the exact top of the market cycle, leaving the company bloated and over-leveraged when the crash arrives. ZIM’s management actively avoided this trap by implementing an exceptionally aggressive dividend distribution policy.
The stated policy mandated returning 30% of quarterly net income to shareholders for the first three quarters of the year, followed by a “step-up” dividend in the fourth quarter designed to bring total annual distributions to between 30% and 50% of full-year net income.25
The execution of this policy resulted in a historic transfer of wealth:
- Since its IPO in January 2021 at $15.00 per share, ZIM has distributed an astonishing $5.7 billion in cash dividends.2
- This equates to $47.54 per share returned directly to investors—more than three times the initial IPO price.2
- For the 2024 fiscal year alone, ZIM paid out $7.98 per share (totaling $961 million), accurately adhering to the target of returning approximately 45% of full-year net income.6
From a strict capital allocation perspective, relentlessly returning cash to shareholders in a low-ROIC, commoditized business is mathematically the correct decision. By systematically stripping excess cash out of the corporate structure rather than reinvesting it at sub-WACC returns, management protected the equity base from future value destruction.
Balance Sheet Resilience
Despite these massive capital outflows, management preserved a highly liquid balance sheet, insulating the company against the inevitable downcycles.
- Total Liquidity: As of Q3 2025, ZIM maintained total cash, bank deposits, and investments of $3.01 billion.14
- Net Debt: Total net debt stood at $2.64 billion.14
- Net Leverage Ratio: The company reported a net leverage ratio of just 0.9x Adjusted EBITDA.14
It is vital to recognize that almost the entirety of ZIM’s $5.9 billion in gross debt consists of capitalized IFRS 16 lease liabilities for its chartered vessels, not traditional bank loans or high-yield corporate bonds.24 A net leverage ratio of 0.9x demonstrates that ZIM retained more than enough liquid cash to cover its near-to-medium-term fixed lease obligations, ensuring robust survivability even if spot rates plunge below breakeven levels in 2026.
Vessel Investment Discipline
While ZIM did commit to 46 newbuild charters in 2021-2022, locking the company into long-term lease liabilities at elevated market rates, this was a necessary operational upgrade rather than reckless expansion. The transition to a 40% LNG-powered fleet drastically lowered the company’s bunker fuel costs and preemptively addressed strict EU environmental regulations.26 By utilizing long-term charters instead of outright purchases, management avoided committing billions in upfront Capex at peak steel prices, maintaining the liquidity necessary to fund the dividend program.
VI. Valuation Analysis
Prior to the announcement of the acquisition on February 16, 2026, ZIM’s equity traded at deeply distressed multiples, reflecting the market’s accurate assessment of the impending 2026 structural downcycle.
Pre-Deal Valuation Context
- Market Capitalization: Approximately $2.7 billion to $3.35 billion.32
- P/E Ratio (TTM): Fluctuated wildly between 1.01x and 3.48x.33 In hyper-cyclical industries, a mid-single-digit P/E is historically a sell signal, as it indicates peak trailing earnings masking an imminent forward earnings cliff.
- Price-to-Book (P/B): Traded at roughly 0.50x to 0.84x.32 Trading at a steep discount to book value highlighted extreme market pessimism regarding future asset utilization and the heavy burden of the capitalized lease liabilities on the balance sheet.
- EV/EBITDA: Traded between 1.3x and 2.08x.34 While optically cheap, Enterprise Value in this context includes the ~$5.9 billion in lease liabilities. The low multiple was purely a function of the inflated TTM EBITDA generated during the 2024 Red Sea rate spike, which the market correctly identified as unsustainable.
Normalized Earnings Power: Attempting to calculate a “normalized” Discounted Cash Flow (DCF) for ZIM is a futile exercise. The company does not possess a steady-state growth rate; it violently oscillates between generating $3.0 billion in operating cash flow and burning hundreds of millions. Over a ten-year cycle, the normalized earnings power of a mid-tier container shipping company functionally equates to its cost of capital. The true equity value of ZIM, absent a geopolitical crisis, is closely tethered to its net tangible asset value and the cash on its balance sheet. This reality was reflected in the “unaffected” stock price of $15.50 in August 2025.2
VII. The Hapag-Lloyd Acquisition & The “New ZIM” Carve-Out
The fundamental analysis of ZIM’s cyclicality and lack of a moat was rendered secondary, if not entirely obsolete, on February 16, 2026. Hapag-Lloyd (XETR: HLAG), the world’s fifth-largest ocean carrier, announced a definitive agreement to acquire 100% of ZIM for $35.00 per share in an all-cash transaction.2
Deal Terms and Financial Mechanics
- Purchase Price: $35.00 per share (100% Cash).
- Total Equity Value: Approximately $4.2 billion.2
- Premium: The offer represents a 58% premium over the pre-announcement closing price of $22.20, and a massive 126% premium over the unaffected price of $15.50 from August 2025.2
- Funding: Hapag-Lloyd will finance the acquisition utilizing its $7.5 billion liquidity reserve, supported by up to $2.5 billion in external bridge financing.1
Strategic Rationale for Hapag-Lloyd
For Hapag-Lloyd, purchasing ZIM at a $4.2 billion equity valuation is a highly strategic, accretive maneuver.
- Scale and Consolidation: The acquisition adds roughly 713,000 TEU of capacity, elevating Hapag-Lloyd’s global market share from ~7.3% to ~9.2%, firmly securing its Top 5 position and closing the gap with COSCO.2
- Trade Lane Dominance: ZIM’s strong network on the Transpacific trade lane immediately elevates Hapag-Lloyd into a top-four position on this critical, high-margin route.2
- Synergies: Hapag-Lloyd management explicitly expects to extract $300 million to $500 million in annual run-rate synergies through network optimization (the single largest driver), procurement consolidation, terminal handling efficiencies, and IT integration.1
- Asset Quality and Decarbonization: Hapag-Lloyd instantly acquires ZIM’s 40 LNG-powered vessels, bypassing shipyard delays and immediately accelerating its own “Strategy 2030” decarbonization goals.1
- The “Net” Price: Crucially, Hapag-Lloyd is acquiring an entity with $3.01 billion in cash and liquidity on its balance sheet.14 Subtracting this cash from the $4.2 billion equity purchase price means Hapag-Lloyd is effectively acquiring the operations, the 40 LNG vessels, and the Transpacific market share for a net cash outlay of barely $1.2 billion (excluding the assumption of the IFRS 16 lease liabilities).
The “Golden Share” and The FIMI Carve-Out
The primary, historical obstacle to any foreign acquisition of ZIM has always been the “Special State Share” (Golden Share) held by the State of Israel. Established during the company’s privatization in 2004, the Golden Share grants the Israeli government absolute veto power over major ownership changes or structural splits. Its explicit purpose is to ensure that a minimum of 11 ships and the company’s headquarters remain under Israeli control to guarantee emergency logistics capability (e.g., transporting munitions, wheat, and fuel) during times of war.4
To bypass this regulatory roadblock and satisfy national security requirements, the transaction utilizes a highly complex, multi-party carve-out structure:
- FIMI Opportunity Funds, Israel’s largest private equity firm (led by Ishay Davidi), will establish a separate, independent Israeli entity internally dubbed “New ZIM”.1
- New ZIM will take ownership of ZIM’s 16 fully owned, Israeli-flagged vessels, the domestic headquarters in Haifa, the ZIM brand name, and assume all legal obligations of the Golden Share.4
- Hapag-Lloyd will acquire the remaining 99 chartered vessels, the highly profitable international commercial routes, and the global agency network.4
- To ensure New ZIM remains a viable “going concern,” Hapag-Lloyd will provide commercial support and slot-charter agreements, granting the downsized Israeli entity access to the broader Gemini Cooperation network.1
VIII. Merger Arbitrage, Pricing Dynamics & Key Risks
Currently, ZIM is no longer a fundamental shipping equity investment; it is entirely a binary geopolitical merger arbitrage play. As of late February 2026, ZIM’s stock is trading in the range of $29.00 to $30.00, representing a massive, highly unusual discount to the $35.00 definitive cash offer.42
At a market price of $29.70, the gross spread to the $35.00 offer is $5.30, or an 17.8% absolute return. Given the expected closing date in late 2026 (roughly 10 months away), this represents an annualized return well in excess of 21%.2 In standard M&A environments, an 18% gross spread on a signed, definitive all-cash agreement indicates severe, systemic market skepticism regarding the probability of the transaction closing.
Dividend Leakage Considerations
Retail investors holding ZIM may anticipate the continuation of the massive “step-up” dividend policy prior to closing. However, merger agreements invariably include strict “Conduct of Business” covenants restricting capital outflows between signing and closing to prevent value leakage. While ZIM may be permitted to pay its “ordinary course” dividend (30% of quarterly net income), a massive 50% step-up payout is highly improbable. Any unauthorized special dividends paid prior to closing would almost certainly result in a dollar-for-dollar downward adjustment to the $35.00 purchase price, ensuring Hapag-Lloyd retains the underlying cash value of the acquired balance sheet.46
Deal Breakers and Asymmetric Downside
The massive 18% arbitrage spread is entirely justified by a confluence of severe, existential risks threatening to terminate the transaction.
1. The Geopolitical Veto Risk (The Primary Threat) The ultimate arbiter of this deal is the Israeli government. Israeli Transport Minister Miri Regev has already actively moved to review and potentially block the transaction, explicitly labeling it a “strategic threat to security”.47
- The Sovereign Ownership Complication: Hapag-Lloyd’s shareholder registry is a geopolitical landmine. The company is 12.3% owned by Qatar Holding LLC (the Qatar Investment Authority) and 10.2% by the Public Investment Fund (PIF) of Saudi Arabia.4 In the context of the ongoing Middle Eastern conflict and Qatar’s perceived ties to adversarial groups, transferring Israel’s primary maritime logistics lifeline to an entity with 22.5% combined Qatari and Saudi sovereign ownership is politically explosive in Jerusalem.
- Viability of New ZIM: The Israeli Shipping and Ports Authority has issued scathing warnings that the FIMI carve-out leaves “New ZIM” dangerously undercapitalized. Without the financial cross-subsidization of ZIM’s highly lucrative global Transpacific routes, a severely downsized fleet of just 16 ships lacks the scale to survive a shipping downcycle. The state fears the new entity will face insolvency, destroying the very emergency logistics capability the Golden Share is meant to protect.37
2. Labor Union Strikes The Histadrut (Israel’s national trade union) and ZIM’s powerful local workers’ committee immediately launched indefinite strikes following the deal’s announcement, completely paralyzing operations at the ports of Haifa and Ashdod.50 The union accurately calculated that the downsized “New ZIM” will only require roughly 120 of the current 1,000 Israeli employees, putting nearly 900 jobs at risk.48 Prolonged, politically mobilized labor disruptions could force the government’s hand to veto the deal.
3. The Asymmetric Downside (The Deal Break Scenario)
If the Israeli government exercises its Golden Share veto and the deal breaks, the downside for ZIM equity is catastrophic.
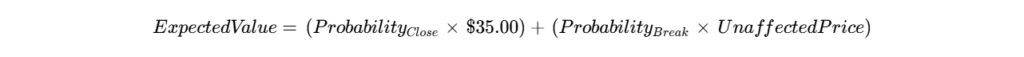
The unaffected stock price in August 2025 was $15.50.2 However, given the expected 25% drop in spot rates, the 11.5m TEU capacity glut expected to drown the market in 2026, and the fact that ZIM would have burned through a year of operating runway, ZIM’s fundamental value in a broken-deal scenario could easily revisit the low teens. Buying ZIM at $29.70 risks a 50%+ capital loss if the political veto is enacted.
IX. Conclusions & Actionable Insights
Evaluated through the stringent, objective framework of competitive advantage, long-term capital compounding, and M&A pricing theory, the following definitive conclusions emerge regarding ZIM Integrated Shipping Services:
1. Is container shipping a “good business” or a commodity hell?
It is strictly a commodity hell. Container shipping requires immense capital, suffers from chronic supply gluts, and offers zero product differentiation. ZIM possesses absolutely no durable competitive advantage or structural moat. Its returns on invested capital are dictated entirely by external macroeconomic forces, supply chain failures, and geopolitical shocks (e.g., pandemics, canal closures) rather than proprietary value creation or operational superiority.
2. Is the asset-light model truly superior?
No. The asset-light charter model is a double-edged sword that simply redistributes risk. By relying on capitalized operating leases rather than owned steel, ZIM achieves extreme operational leverage. This generates parabolic, industry-leading ROE during capacity crunches but creates dangerous, inflexible fixed-cost burdens when freight rates inevitably collapse. It shifts the location of the leverage but does not eliminate the cyclical risk.
3. Is management prudently managing capital?
Yes. In a rare and commendable display of discipline for a hyper-cyclical industry, CEO Eli Glickman and the board of directors accurately recognized the temporary nature of their windfall profits. Rather than incinerating capital on value-destroying M&A or vanity projects at the peak of the cycle, they distributed an unprecedented $5.7 billion in cash directly to shareholders and preserved balance sheet liquidity. They subsequently negotiated a $4.2 billion buyout at a 126% premium to unaffected prices at the exact moment the industry faced a structural downcycle. This represents elite-level capital extraction and monetization of a fundamentally flawed business model.
4. At current valuations, does ZIM offer an asymmetric risk/reward?
Currently, ZIM is completely detached from shipping fundamentals; it is entirely a negatively skewed, high-risk geopolitical merger arbitrage play.
- The Reward: An 18% gross spread (buying at ~$29.70 for a fixed $35.00 cash exit).
- The Risk: A 50%+ catastrophic downside (falling back to $14-$15) if the Israeli government invokes its Golden Share veto.
Given the highly politicized nature of the Israeli government’s veto power, the deep national security concerns surrounding Hapag-Lloyd’s Qatari and Saudi sovereign ownership, and the active, paralyzing labor strikes at Israeli ports, the probability of the deal breaking or requiring severe, value-destructive renegotiation is materially higher than a standard corporate antitrust review. Investors should not mistake the 18% arbitrage yield for easy alpha; it is an accurate reflection of the severe existential risk to the transaction’s completion.
Frequently Asked Questions
General Questions
- What thoughtful questions have other investors asked about this company? During recent 2025 earnings calls, analysts focused heavily on the timing of revenue recognition, inventory levels, and the potential for early peak seasons. They also questioned management extensively on strategies for cost management, efficiency gains in a declining rate environment, and the risks surrounding expensive vessel charter renewals as industry overcapacity looms.
Cyclicality & Earnings Nature
- Are earnings at a cyclical high or cyclical low? Earnings have just passed a cyclical high (peaking in 2024 with a net income of $2.15 billion) and are currently plunging toward a cyclical low. By Q3 2025, net income collapsed 89% year-over-year to $123 million as freight rates normalized.
- Are earnings driven primarily by the external environment or internal company actions? They are almost entirely driven by the external macro environment. Ocean carrier earnings are highly leveraged to average spot freight rates, which are currently dictated by exogenous factors like Red Sea vessel diversions, US-China tariffs, and global vessel supply.
- How stable are revenues? Highly unstable. Revenues swing violently with global supply chains. For example, full-year 2024 revenues surged 63% year-over-year to $8.43 billion , but by Q3 2025, quarterly revenues dropped 36% year-over-year to $1.78 billion.
- Outlook for the company’s products and services? The standalone fundamental outlook is bleak. The industry is facing a massive structural downcycle in 2026, with global average spot rates forecast to fall 25% due to a historic influx of new vessel capacity. However, this is largely superseded by the impending $4.2 billion buyout by Hapag-Lloyd.
- How big will this market be? Is it growing? Shrinking? Domestic or international? It is a massive international market moving 95% of global trade worth $10.2 trillion. Underlying global container shipping demand is forecast to grow by roughly 3% in 2026, but the fleet supply is growing faster at 3.6%, creating a shrinking profit pool.
Business Quality & Competitive Moat
- Is the industry getting more or less competitive? More competitive and highly consolidated. The top 10 operators control ~85% of the market. The formation of new megastructures like the Gemini Cooperation (Maersk and Hapag-Lloyd) is intensifying competition, especially as carriers fight to fill a record orderbook of new ships in 2026.
- How profitable is this business? What is the return on capital invested? Return on equity? Profitability is violently cyclical. ROE was recently reported at 25.3%. Historical ROIC demonstrates extreme volatility: 160.5% during the 2021 boom, crashing to -28.0% in 2023, and stabilizing temporarily around 12.7% to 15.2% in late 2025.
- How profitable is this industry? Are there a lot of competitors? What are the barriers to entry? The industry is a commoditized oligopoly characterized by boom-and-bust profit cycles. Barriers to entry are immense, requiring massive capital outlays for vessels, complex global logistics infrastructure, port access agreements, and compliance with tightening environmental regulations like the EU ETS.
- Can this business be easily understood? The core mechanism—transporting containers across oceans for a fee—is simple. However, the macroeconomic variables driving the freight rates (geopolitics, canal water levels, global GDP multipliers, and alliance structures) are highly complex.
- Can this company be undermined by foreign, low-cost labor? No. Labor is a relatively minor cost compared to vessel charter hires, port fees, and bunker (fuel) expenses.
- Do brands matter? Very little. Container shipping is a strictly commoditized service where price and schedule reliability dictate customer choices.
- What is the nature of competition? It is a price-taking environment where scale dictates unit costs. Carriers compete on network coverage, capacity, and increasingly, sustainability (LNG/methanol fleets).
- What are the customers switching costs? Extremely low. Freight forwarders and shippers regularly switch carriers to secure the lowest spot rates or the most reliable weekly schedules.
Financial Condition & Balance Sheet
- Does the company have assets that are not fully recognized in the balance sheet? ZIM operates an “asset-light” model where ~87% of its fleet is chartered. It holds long-term charter agreements and purchase options on several vessels (including new LNG dual-fuel ships) which gives it control over capacity without the full upfront ownership costs on its balance sheet.
- What off-balance sheet liabilities does the company have? Its primary liabilities are long-term vessel leases, which are capitalized on the balance sheet as right-of-use liabilities under IFRS 16. As of the end of 2024, ZIM carried $5.92 billion in lease liabilities maturing between 2025 and 2038.
- How conservative is the company’s accounting? It adheres to standard IFRS. Management is willing to take realistic writedowns; in 2023, they recorded a massive $2.06 billion non-cash impairment charge on assets when the market outlook deteriorated.
- How CapEx hungry is this business? Traditionally, it requires massive Capex. ZIM bypasses traditional Capex by chartering ships, but this just shifts the burden into massive operating lease obligations. Recently, however, ZIM committed $2.3 billion in charter hire agreements for 10 new LNG vessels.
Capital Allocation & Management
- How much free cash flow does the business generate? How does management use this free cash flow? What is their philosophy? FCF generation is massive during upcycles ($3.55 billion for FY 2024) but collapses during downcycles ($574 million in Q3 2025). Management’s philosophy is an aggressive capital return strategy, historically paying out 30% to 50% of annual net income. They have returned $5.7 billion to shareholders in dividends since their 2021 IPO.
- Has the company made any significant acquisitions recently? No. Instead, ZIM is the target of an acquisition. In February 2026, Hapag-Lloyd signed a definitive agreement to acquire ZIM for $4.2 billion.
- Is the company buying back shares? No. Management explicitly prioritizes massive dividend payouts over share repurchases.
- Does the company issue large amounts of new shares to insiders? No unusual issuance is noted. Executive compensation includes standard Restricted Stock Units (RSUs) and Performance RSUs.
- What is the compensation policy of directors and management? Compensation is tied to ZIM’s long-term financial goals using equity-based awards. The policy includes “change in control” provisions where option awards can vest on an accelerated basis if the executive is terminated without cause following a buyout.
- What are the motivations of management? Management is highly financially motivated to maximize shareholder exits. CEO Eli Glickman previously attempted a management buyout in 2025 that was rejected as too low, before pivoting to support the much higher $4.2 billion Hapag-Lloyd cash buyout.
Valuation & Market Data
- Is the stock an ADR? MLP? K-1? ZIM is an Israeli foreign private issuer listed directly on the NYSE as an ordinary share, not an ADR. However, its dividends are subject to a 25% Israeli withholding tax. US investors receive standard tax forms (like a 1099-DIV) but must file for a Foreign Tax Credit (often Form 1116) to avoid double taxation.
- Dividend Policy? ZIM’s stated policy is to distribute 30% of quarterly net income for the first three quarters, with a potential “step-up” dividend in Q4 to bring the cumulative annual payout to 30%–50% of net income.
- How profitable is this business? Highly profitable only during macro supply shocks. Net margin reached 26% in 2024 but fell to 15% in Q3 2025, and operating margins dropped from 45% in Q3 2024 to 15% in Q3 2025.
- Is net income diverging from cash from operations? Yes, frequently. Due to the heavy depreciation of leased assets and occasional impairment charges, operating cash flow usually exceeds net income. For example, in Q3 2025, net income was $123 million, while cash generated from operating activities was $628 million.
Risks & Downside
- What factors would cause the stock to decline? The primary immediate risk is the Israeli government exercising its “Golden Share” to veto the Hapag-Lloyd acquisition, or prolonged domestic labor strikes paralyzing the company. If the deal breaks, the stock will re-price to fundamental shipping economics, which face a severe overcapacity downcycle in 2026.
- What is the risk of a catastrophic loss? High, in the context of merger arbitrage. The $35.00 cash buyout is a 126% premium over the unaffected stock price of $15.50. If the deal is blocked, shares could easily plummet >50% back to unaffected levels.
- Chance of a total loss? Virtually zero. ZIM maintains an extremely liquid balance sheet with over $3.0 billion in cash and a low net leverage ratio of 0.9x.
Recent News & Events
- Has the business environment changed recently? Yes. The transient pricing power afforded by the Red Sea crisis evaporated in late 2025. Spot freight rates plunged 35% year-over-year in Q3 2025 , signaling a return to structural overcapacity.
- Has the company made any significant acquisitions recently? No. It is the target of a $4.2 billion buyout by German carrier Hapag-Lloyd, announced in February 2026.
- Has the company recently changed accounting policies? No significant accounting changes have been reported.
- Recent changes in the business, new markets, new production facilities, what’s changed recently? New management? The company is undergoing a massive structural change. To satisfy Israel’s national security “Golden Share,” ZIM is being carved up: Israeli private equity firm FIMI will acquire 16 vessels, domestic routes, and the ZIM brand to create “New ZIM,” while Hapag-Lloyd absorbs the global international routes and 99 chartered ships. This has triggered an indefinite labor strike by ZIM’s Israeli workers and sparked active intervention attempts by the Israeli Transport Minister to block the deal.
Works cited
- Investor Presentation – Hapag-Lloyd, accessed February 19, 2026, https://www.hapag-lloyd.com/content/dam/website/downloads/ir/Investor_Presentation_HLAG_ZIM.pdf
- Hapag-Lloyd’s $4.2 Billion ZIM Acquisition Reshapes Global, accessed February 19, 2026, https://gcaptain.com/hapag-lloyds-4-2-billion-zim-acquisition-reshapes-global-container-shipping-map/
- Global Trade Shift: Hapag-Lloyd Snaps Up ZIM in $4.2B Deal, accessed February 19, 2026, https://www.globaltrademag.com/global-trade-shift-hapag-lloyd-snaps-up-zim-in-4-2b-deal/?gtd=3850&scn=
- Hapag-Lloyd, FIMI to acquire Israel’s ZIM in $3.5B+ takeover, accessed February 19, 2026, https://www.ynetnews.com/business/article/bykwowjdbg
- Global Trade Shift: Hapag-Lloyd Snaps Up ZIM in $4.2B Deal, accessed February 19, 2026, https://www.globaltrademag.com/global-trade-shift-hapag-lloyd-snaps-up-zim-in-4-2b-deal/
- ZIM Reports Financial Results for the Fourth Quarter and the Full, accessed February 19, 2026, https://investors.zim.com/news/news-details/2025/ZIM-Reports-Financial-Results-for-the-Fourth-Quarter-and-the-Full-Year-of-2024/default.aspx
- Investor Presentation Q4 & FY 2024 FINANCIAL RESULTS, accessed February 19, 2026, https://s203.q4cdn.com/172866090/files/doc_financials/2024/q4/Q4FY-2024-Investor-Presentation-Final-updated-FLS-12-3-2025.pdf
- How do Red Sea disruptions affect global supply chains?, accessed February 19, 2026, https://www.hermes-investment.com/de/de/professional/insights/alternatives/how-do-red-sea-disruptions-affect-global-supply-chains/
- The Impact of the Red Sea Crisis on Global Shipping and Strategic, accessed February 19, 2026, https://www.researchgate.net/publication/396450659_The_Impact_of_the_Red_Sea_Crisis_on_Global_Shipping_and_Strategic_Supply_Chain_Management
- Dual Impact: Red Sea Tensions, Surging Demand Drive Ocean, accessed February 19, 2026, https://reallogistics.vn/market-updates/dual-impact-red-sea-tensions-surging-demand-drive-ocean-freight-rates-and-capacity-in-2025
- 2026 Container Shipping Outlook: | AlixPartners, accessed February 19, 2026, https://www.alixpartners.com/media/s12pyi2i/2026-container-shipping-outlook-sli01sig2026.pdf
- CONTAINER SHIPPING MARKET OUTLOOK 2025, accessed February 19, 2026, http://bipc.kr/regi/upload/[%EC%84%B8%EC%85%981-2]%20Hua%20Joo%20TAN.pdf
- Investor Presentation Q2 2025 FINANCIAL RESULTS, accessed February 19, 2026, https://s203.q4cdn.com/172866090/files/doc_financials/2025/q2/Q2-2025-Investor-Presentation-FINAL.pdf
- ZIM Reports Financial Results for the Third Quarter of 2025, accessed February 19, 2026, https://s203.q4cdn.com/172866090/files/doc_news/ZIM-Reports-Financial-Results-for-the-Third-Quarter-of-2025-2025.pdf
- ZIM Reports Financial Results for the Third Quarter of 2024, accessed February 19, 2026, https://www.hellenicshippingnews.com/zim-reports-financial-results-for-the-third-quarter-of-2024-raises-full-year-2024-guidance/
- Container Shipping Financial Health Check 2026 – Drewry, accessed February 19, 2026, https://www.drewry.co.uk/maritime-research-products/maritime-research-products/container-shipping-financial-health-check-2026
- 2026 Ocean Outlook – Xeneta, accessed February 19, 2026, https://www.xeneta.com/hubfs/2026%20Ocean%20Outlook.pdf
- Intra-Asia trade: Maersk, Hapag-Lloyd and PIL biggest winners, accessed February 19, 2026, https://globalmaritimehub.com/intra-asia-trade-maersk-hapag-lloyd-and-pil-biggest-winners.html
- What is Competitive Landscape of ZIM Integrated Shipping Services, accessed February 19, 2026, https://matrixbcg.com/blogs/competitors/zim
- Global Container Lines Rankings by TEU Capacity, accessed February 19, 2026, https://container-news.com/container-lines-rankings-2025/
- Top 30 Ocean Carriers of 2025: Ranking the Biggest Operators, accessed February 19, 2026, https://www.supplychain247.com/article/top-30-ocean-carriers-2025
- Investor Presentation Q 3 2025 FINANCIAL RESULTS, accessed February 19, 2026, https://s203.q4cdn.com/172866090/files/doc_financials/2025/q3/Q3-2025-Investor-Presentation-20-11-2025-FINAL.pdf
- Hapag-Lloyd closes in on ZIM takeover – Splash247, accessed February 19, 2026, https://splash247.com/hapag-lloyd-closes-in-on-zim-takeover/
- Submission Proof – \\fs\edgar\EDGAR Filing\ZIM Integrated Shipping …, accessed February 19, 2026, https://s203.q4cdn.com/172866090/files/doc_financials/2024/ar/ZIM-2024-20F-F-S.pdf
- ZIM Investor Update (December 2025), accessed February 19, 2026, https://s203.q4cdn.com/172866090/files/doc_financials/2025/ar/ZIM-Investor-Update-December-2025-web.pdf
- How Does ZIM Integrated Shipping Services Company Work?, accessed February 19, 2026, https://matrixbcg.com/blogs/how-it-works/zim
- ZIM – Investor Relations, accessed February 19, 2026, https://investors.zim.com/overview/default.aspx
- ZIM (ZIM Integrated Shipping Services) ROIC % – GuruFocus, accessed February 19, 2026, https://www.gurufocus.com/term/roic/ZIM
- ROE – ZIM Integrated Shipping Services Ltd (NYSE:ZIM), accessed February 19, 2026, https://www.alphaspread.com/security/nyse/zim/profitability/ratio/return-on-equity
- ZIM Integrated Shipping Services (ZIM) | Sure Dividend, accessed February 19, 2026, https://www.suredividend.com/wp-content/uploads/2024/03/ZIM-2024-03-13.pdf
- ZIM Integrated Shipping Services (ZIM) – Operating Margin, accessed February 19, 2026, https://companiesmarketcap.com/zim/operating-margin/
- ZIM Integrated Shipping Services – Forbes, accessed February 19, 2026, https://www.forbes.com/companies/zim-integrated-shipping-services/
- ZIM Integrated Shipping Services (NYSE:ZIM) Sees Strong Trading, accessed February 19, 2026, https://www.marketbeat.com/instant-alerts/zim-integrated-shipping-services-nysezim-sees-strong-trading-volume-should-you-buy-2026-02-18/
- ZIM — Buy | 66.7 Score | ZIM Integrated Shipping Services Ltd., accessed February 19, 2026, https://www.blankcapitalresearch.com/stocks/ZIM
- Breaking Down ZIM Integrated Shipping Services Ltd. (ZIM), accessed February 19, 2026, https://dcfmodeling.com/blogs/health/zim-financial-health
- OCEAN FREIGHT MARKET UPDATE – DHL, accessed February 19, 2026, https://lot.dhl.com/wp-content/uploads/2025/02/lot_67ac4abc492b07.60484851.pdf
- Inside Zim’s $4.2 billion high-stakes sale to Hapag-Lloyd – CTech, accessed February 19, 2026, https://www.calcalistech.com/ctechnews/article/bsmjvyksq
- ZIM Integrated Shipping Services Ltd (ZIM) Financial Ratios, accessed February 19, 2026, https://www.investing.com/equities/zim-integrated-shipping-services-ratios
- ZIM (ZIM Integrated Shipping Services) EV-to-EBITDA – GuruFocus, accessed February 19, 2026, https://www.gurufocus.com/term/enterprise-value-to-ebitda/ZIM
- Hapag-Lloyd signs merger agreement with ZIM, accessed February 19, 2026, https://www.hapag-lloyd.com/en/company/press/releases/2026/02/hapag-lloyd-signs-merger-agreement-with-zim.html
- What Does Hapag-Lloyd’s Acquisition Mean for ZIM Shareholders, accessed February 19, 2026, https://www.kavout.com/market-lens/what-does-hapag-lloyd-s-acquisition-mean-for-zim-shareholders
- Shipping Shock: ZIM Shareholders Secure Massive Cash Exit, accessed February 19, 2026, https://www.nasdaq.com/articles/shipping-shock-zim-shareholders-secure-massive-cash-exit
- Hapag-Lloyd to Acquire ZIM Integrated Shipping for $4.2 Billion, accessed February 19, 2026, https://markets.financialcontent.com/stocks/article/marketminute-2026-2-17-hapag-lloyd-to-acquire-zim-integrated-shipping-for-42-billion
- Could gov’t use golden share to force El Al to cut fares? – Globes, accessed February 19, 2026, https://en.globes.co.il/en/article-could-govt-use-golden-share-to-force-el-al-to-cut-fares-1001491273
- ZIM Integrated Shipping (ZIM) Stock Climbs 34% Following Hapag, accessed February 19, 2026, https://parameter.io/zim-integrated-shipping-zim-stock-climbs-34-following-hapag-lloyd-takeover-announcement/
- r/zim – Reddit, accessed February 19, 2026, https://www.reddit.com/r/zim/hot/?after=MjQ%3D&sort=best&t=DAY
- Transport Minister Moves to Block ZIM Deal: “Strategic Threat to, accessed February 19, 2026, https://en.port2port.co.il/article/Sea-Transport/Liner-Shipping/Transport-Minister-Moves-to-Block-ZIM-Deal-Strategic-Threat-to-Security/
- Why a German shipping deal alarms Israel’s government, accessed February 19, 2026, https://www.hellenicshippingnews.com/why-a-german-shipping-deal-alarms-israels-government/
- Israeli Opposition Emerges as Hapag-Lloyd Signs Deal to Acquire Zim, accessed February 19, 2026, https://maritime-executive.com/article/israeli-opposition-emerges-as-hapag-lloyd-signs-deal-to-acquire-zim
- Strike hits Israel’s national shipping company over planned sale, accessed February 19, 2026, https://english.news.cn/20260216/da12a9729b0141f4bd3bff2f3e09db69/c.html
- Striking Workers Paralyse ZIM Over Takeover Fears – Ships & Ports, accessed February 19, 2026, https://shipsandports.com.ng/striking-workers-paralyse-zim-over-takeover-fears/